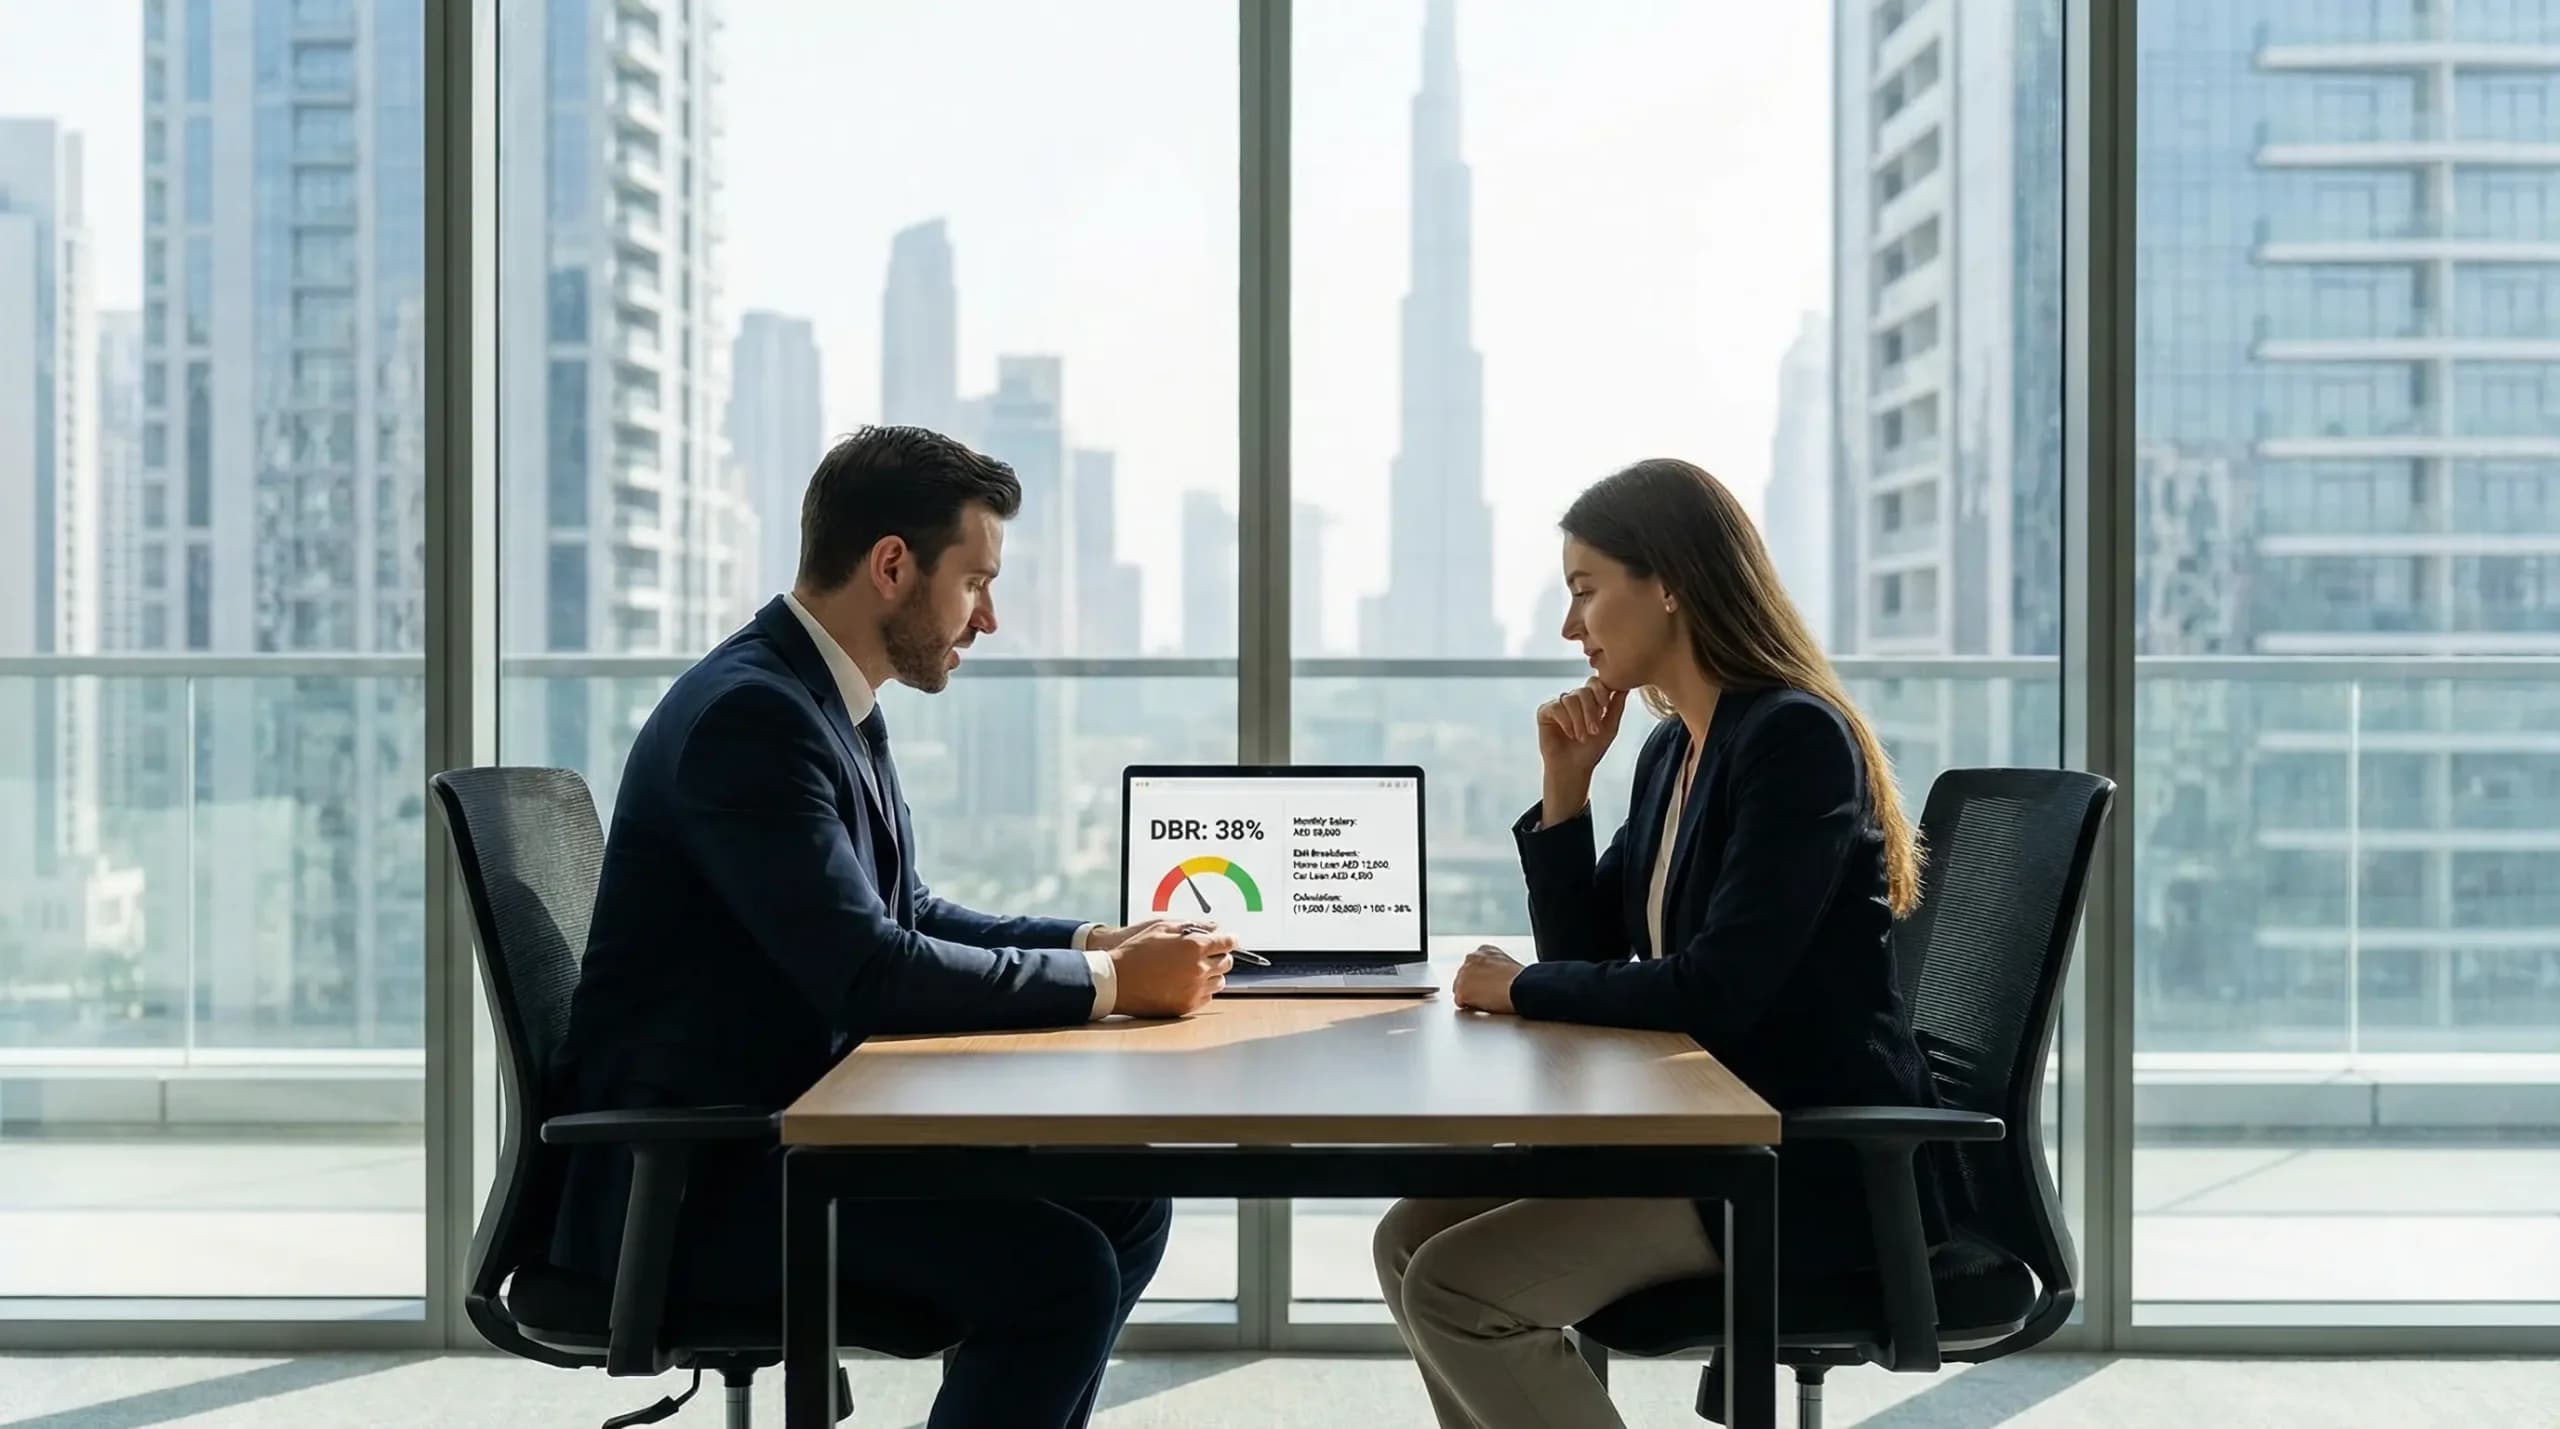
Your Debt Burden Ratio is the share of your gross monthly income that’s already committed to repaying debt. In the UAE the Central Bank caps it at 50%, and that cap includes the mortgage you’re applying for. If your existing commitments plus the new mortgage payment cross half your income, the bank can’t approve you, no matter how much it likes you.
It’s the reason two people on the same salary walk out of the same bank with very different answers.
Most people meet DBR for the first time in a rejection letter, usually described vaguely as “affordability.” This guide is the version you want before you apply, not after.
Someone earning AED 30,000 with AED 200,000 in combined limits has spent two-thirds of their headroom before a single loan enters the picture, on a zero balance.
This is why long-standing residents with spotless credit sometimes get startlingly small offers. Years in the UAE tend to mean accumulated cards, and every limit increase you’ve ever accepted has quietly shrunk what you can borrow for a home.
The fix is the fastest lever you have. Close cards you don’t use, or ask for lower limits on the ones you keep, and do it early enough that the change reaches your credit file before the bank pulls it.
At current rates over 25 years, that supports a loan of roughly AED 1.4 million, rather than the AED 2 million the salary alone might suggest.
Cancel two unused cards, bring total limits down to AED 20,000, and the card deduction drops to AED 1,000. Headroom rises to AED 9,500. An afternoon of admin, worth somewhere around AED 380,000 in extra borrowing capacity.
You can put your own numbers through our mortgage calculator, or run a fuller check with the eligibility calculator.
Stressed, the mortgage they needed cost around AED 9,300 a month. They were roughly AED 3,500 short, and the decline letter said almost nothing useful.
Three months later, same couple, same salary, same property:
The loan cleared comfortably. Nothing about their income changed. Around AED 6,000 a month came back from credit limits they weren’t using.
Not every decline unwinds this neatly, but a lot of them are closer to this than people assume. If you’ve already had a no, it’s worth reading why Dubai mortgages get rejected and our case study on turning a rejection into an approval in seven days.
What is debt burden ratio?
DBR stands for Debt Burden Ratio. You’ll see it written as debt-burden ratio, or just DBR (%), on bank forms. If you’ve borrowed elsewhere in the world you’ll know the same idea as debt-to-income, or DTI. The maths is identical. DBR is simply the term UAE banks and Central Bank regulation use.The formula
DBR = (total monthly debt commitments ÷ gross monthly income) × 100 Gross means before deductions. Because there’s no personal income tax here, gross and net are usually the same number on an expat salary, though pension contributions can open a small gap for UAE nationals. Suppose you earn AED 30,000 a month and your existing commitments come to AED 6,000. Your DBR right now is 20%. That leaves 30% of your income, or AED 9,000 a month, available for a mortgage payment. That leftover figure is what really answers the question “how much can I borrow.” Your salary gets you into the conversation. Your DBR decides how it ends.Where the 50% cap comes from
This isn’t a bank policy you can negotiate around. It sits in the Central Bank of the UAE’s Regulations Regarding Mortgage Loans, issued as Circular No. 31/2013, which states that the DBR cannot exceed 50%. Every licensed lender in the country applies it.Why some banks stop well before 50%
What varies between lenders is how much of that 50% they’re actually willing to use. Plenty of banks set internal ceilings below the regulatory limit, often somewhere in the 40% to 48% range, and they apply them more tightly to self-employed applicants and larger loan sizes. There’s a second layer too. The regulation requires the assessment to include an allowance for normal recurring household spending, on top of your other liabilities. So an underwriter looking at a file that technically passes at 49% is entitled to ask whether what’s left over is enough to live on, and to decline if the answer looks thin. A marginal pass isn’t really a pass. It’s a file that gets read very slowly.What counts towards your DBR
Counted in full
- Personal loan instalments
- Car loan instalments
- Existing mortgage payments on other properties
- Any other facility with a fixed monthly repayment
- The new mortgage payment you’re applying for
Not counted
Rent, utilities, school fees, insurance premiums, groceries and general living costs sit outside the calculation. Rent is treated as a living expense rather than a debt. The exception is if you’ve financed your rent through a rent loan or an instalment plan on a credit facility, in which case that repayment does count.How credit cards are counted
This is where most applications quietly lose their borrowing power, and it catches out people who consider themselves debt-free. Banks don’t count what you owe on a card. They count what you could owe. The standard treatment is to take roughly 5% of your total credit card limit and treat it as a monthly commitment, whatever your balance happens to be. A card you’ve never activated still counts.| Total card limits | Counted against you each month |
| AED 20,000 | AED 1,000 |
| AED 50,000 | AED 2,500 |
| AED 100,000 | AED 5,000 |
| AED 200,000 | AED 10,000 |
The bank checks your file, not your word
You won’t be taken at your word on any of this. The lender pulls your Al Etihad Credit Bureau report and counts every live liability on it, including the card you forgot about and the loan you guaranteed for a relative. That’s the most common surprise in a UAE mortgage application, and it’s entirely avoidable. Pull your own report before the bank does. We’ve covered how to check your credit score in the UAE, and separately what minimum credit score you need for a loan, since the two get confused constantly.Two worked examples
A straightforward case
A salaried expat earning AED 25,000 a month, with a car loan of AED 2,000 and credit card limits totalling AED 60,000 that they clear every month.| DBR ceiling (50% of 25,000) | AED 12,500 |
| Car loan | −AED 2,000 |
| Cards at 5% of AED 60,000 | −AED 3,000 |
| Available for a mortgage | AED 7,500/month |
A decline, and what fixed it
Closer to what a real rejection looks like. A couple applying jointly for a AED 2.2 million apartment with 20% down, so a loan of AED 1.76 million.| Combined gross income | AED 40,000 |
| DBR ceiling | AED 20,000 |
| Car-related personal loan | −AED 3,400 |
| Furniture and fit-out loan | −AED 1,800 |
| Four cards, limits of AED 180,000 | −AED 9,000 |
| Headroom | AED 5,800/month |
| Two cards closed, limits cut to AED 60,000 | −AED 3,000 |
| Furniture loan settled from savings | −AED 0 |
| Car loan unchanged | −AED 3,400 |
| Headroom | AED 13,600/month |
The tests that shrink your borrowing power
You’re assessed on a higher rate than you’ll pay
Your DBR isn’t calculated at the rate you’ve been quoted. The Central Bank requires lenders to stress test the loan at 2 to 4 percentage points above the current rate, with the size of the buffer depending on where rates sit in the cycle. A mortgage quoted at 3.99% gets assessed somewhere in the region of 6% to 8%. The payment in your DBR calculation is bigger than the payment you’ll actually make.The reversion rate catch
Here’s the part that surprises people, and it’s written into the regulation. Where an introductory or fixed rate applies, the stress test has to be run against the rate that kicks in once that period ends, not the headline rate. So a very attractive two-year fixed offer doesn’t automatically buy you a bigger loan. The bank is testing you against the reversion rate plus the buffer. If you’re weighing a short teaser against a longer fixed term, our comparison of fixed versus variable mortgages in the UAE explains what happens at the end of the fixed period, and how EIBOR feeds into your rate covers the benchmark those reversion margins sit on top of.Buying to let? Two months come off the rent
If the property is for investment, the regulation requires lenders to deduct at least two months of rental income from the calculation, to allow for void periods between tenants. Investors tend to build their case on twelve months of rent. The bank builds its case on ten. On a unit renting at AED 90,000 a year, that’s AED 15,000 of income you simply don’t get credit for. Plan on ten months. If the numbers only work on twelve, they don’t work.What income banks will actually count
Not every dirham you earn carries the same weight. Counted: basic salary, guaranteed and documented allowances, verifiable business income, and rental income after the deduction above. Discounted or excluded: bonuses, commission and other non-standard or temporary income. The regulation says these should be suitably discounted, or excluded altogether where they aren’t guaranteed. If a large slice of your package is variable, expect the bank to credit you with considerably less than your total earnings. Never counted: end-of-service gratuity. Using it as a source of repayment is prohibited outright.If you’re self-employed
Banks typically apply an income haircut of 20% to 40% to business earnings before the DBR is even calculated, on top of asking for two years of trade licence history and audited financials. That haircut is the mechanical reason profitable business owners get declined on paper. It’s also the reason a second, better-prepared submission so often succeeds. How the income is documented and presented changes the number the underwriter works from. If you’re a business owner buying through your company rather than personally, commercial property finance is assessed on different ground again.If you’re buying from overseas
Non-residents face the same 50% cap, but two things complicate it. Foreign income has to be converted to dirhams, and banks usually apply their own exchange assumption or an extra haircut on top, so the income you’re credited with can sit well below what you actually earn. Overseas liabilities also need documenting, and they don’t appear on an AECB report the way UAE facilities do, which puts the burden of evidence on you. None of that makes the ratio harder to pass. It makes the file slower to build, and it means lender choice matters more than usual, since only a handful of UAE banks actively underwrite overseas income. Our non-resident finance page covers who lends and on what terms, and there’s more detail in our guide to getting a Dubai mortgage as a non-resident.A note on Islamic finance
DBR applies in exactly the same way to Sharia-compliant products. An Ijara or Murabaha facility is assessed against the same 50% ceiling, the same stress test and the same credit card treatment. The structure of the contract changes; the affordability arithmetic doesn’t. If that’s the route you’re considering, see how Islamic mortgages work in the UAE or our Islamic home finance options.When the cap isn’t 50%
Retirees are capped at 30%. For pensioners, DBR must not exceed 30% of regular income, under Article 7-2 of Notice No. 2901/2011, and the bank has to apply the lower figure as soon as it becomes aware you’ve retired. You’ll see 35% quoted in a fair few places online. It’s 30%. Loans running past retirement age. Where the repayment schedule extends beyond your expected retirement, the lender has to be satisfied the outstanding balance can still be serviced at 50% of your post-retirement income. Take a 25-year term at 48 and part of your assessment rests on income you don’t have yet. Salary reductions. If your income falls for reasons other than retirement, a bank can restore compliance by extending the tenor so repayments sit at 50% of the reduced salary, rather than calling in the facility. UAE nationals, non-investment homes. A 2023 relief measure lets banks exceed the 50% deduction up to a maximum of 60% where monthly income is AED 40,000 or above, to absorb rate increases. Below AED 40,000, banks may instead extend the tenor to a maximum of 30 years. The bank absorbs the remaining uncovered interest in both cases.DBR and your credit score are different tests
These get conflated constantly, which leads people to fix the wrong thing. Your AECB score, issued by the Al Etihad Credit Bureau on a 300 to 900 scale, measures behaviour: have you repaid on time, have you defaulted, how long is your history. It answers whether you’ll pay the bank back. Your DBR measures capacity. It answers whether you can afford another payment at all. You can pass one and fail the other in either direction. A spotless 780 score alongside AED 200,000 of card limits still fails on DBR. Plenty of headroom with two missed payments last year still fails on score. Banks look at both, and a strong score buys you no exemption from the cap. There is one place they touch. Credit utilisation, meaning how much of your limits you’re actually using, feeds your score. So paying balances down helps the score, while cutting the limits themselves helps the DBR. Do both, in that order, so you’re not reducing a limit while a balance is still sitting against it.How to lower your DBR before you apply
- Cut your credit card limits. Every AED 20,000 removed hands back roughly AED 1,000 a month of headroom.
- Close cards you don’t use. A dormant card isn’t a neutral card.
- Clear small loans first. Settling a AED 1,200 monthly instalment is worth around AED 220,000 of borrowing capacity at current rates.
- Pull your credit bureau report first. Find anything forgotten or inaccurate, and dispute errors in writing before you apply.
- Request liability letters early. Banks want confirmed outstanding balances, not your estimates, and chasing these late is a routine cause of delay.
- Consider a longer tenor. A 25-year term produces a smaller monthly payment than a 20-year one, which lowers the DBR hit. It costs more in total interest, so it’s a trade-off, and it interacts with the age-at-maturity limit.
- Open nothing new. No car loan, no buy-now-pay-later, no extra card in the six months before you apply.
- Restructure an existing mortgage. If you already hold a mortgage on another property, a mortgage buyout or balance transfer that lowers the existing payment can free up room for the new one.
Mistakes we see most often
- Applying to several banks at once after a decline. Each application leaves a footprint, a cluster of them reads badly, and none of it addresses the ratio underneath.
- Assuming cards don’t matter because you clear them monthly. Your balance is irrelevant to the calculation.
- Budgeting on the headline rate when affordability is assessed on the stressed reversion rate.
- Forgetting that LTV runs alongside DBR. Passing on affordability doesn’t make the loan size available. Loan-to-value caps apply separately, and whichever limit is lower is the one that binds. Our guide to UAE mortgage LTV rules for expats and nationals sets out the ceilings, and the wider expat mortgage rules and fees guide covers what else you’ll need in cash. There are a few more of these in our list of mortgage mistakes to avoid in Dubai.
- Treating 49% as a pass. At that level you’re relying on an underwriter’s view of your cost of living. Leave yourself room.
The rules at a glance
Almost everything on this page comes from one document: the Central Bank of the UAE’s Regulations Regarding Mortgage Loans, issued as Circular No. 31/2013. It’s split into numbered articles, and the one that matters most here is Article 3, “Important Ratios”, which is where the DBR cap, the stress test and the rental deduction all live. You can read it yourself on the Central Bank’s public rulebook, linked in the table below.| Rule | What it says | Where it comes from |
| DBR cap | 50% of gross monthly income, including the new loan | Article 3, Important Ratios |
| Stress test | 2 to 4 percentage points above the current rate | Article 3 |
| Introductory rates | Test applies to the reversion rate, not the teaser | Article 3 |
| Investment property | At least two months’ rental income deducted | Article 3 |
| Beyond retirement age | Balance serviceable at 50% of post-retirement income | Article 3 |
| Maximum tenor | 25 years | Article 3 |
| End-of-service gratuity | Not permitted as a source of repayment | Article 3 |
| Variable income | Bonuses and non-guaranteed income discounted or excluded | Regulations Regarding Mortgage Loans |
| Household costs | Allowance for recurring living expenses must be included | Regulations Regarding Mortgage Loans |
| Retirees | 30% of regular income, applied as soon as the bank knows | Article 7-2, Notice No. 2901/2011 |
| Credit cards | Around 5% of total limit counted monthly | Standard bank underwriting practice, not written regulation |