If you hold a variable-rate mortgage in the UAE, there’s a strong chance one number decides your payment: the three-month EIBOR fixing.
Brokers report that most UAE variable mortgages reference it, with a minority on one-month, some on six-month and few on twelve-month. HSBC even markets a product by that name — the Variable 3-Month EIBOR home loan. It has become the market default.
What that means practically is a payment that recalculates four times a year, in steps rather than smoothly. In a stable market you barely notice. In 2022, four consecutive resets raised a typical payment by 46%.
AED 3,032 a month more, or AED 36,385 a year — a 46% increase across four resets.
An independent figure from the market corroborates the scale: a Dubai mortgage manager quantified the March 2022 to 2023 move as roughly AED 4,000 extra per month on a AED 1 million loan over 25 years.
Roughly AED 230 per month for every 25 basis points on a AED 1.5 million balance. Scale proportionally: about AED 150 on AED 1 million, about AED 300 on AED 2 million.
That’s the number to stress-test your own budget against. The Fed raised in September 2026 and a majority of FOMC members projected another increase before year end, so a 25 to 50 basis point move at your next reset is a reasonable planning assumption rather than a worst case.
Model your own figures on our mortgage calculator.
The current 3-month fixing
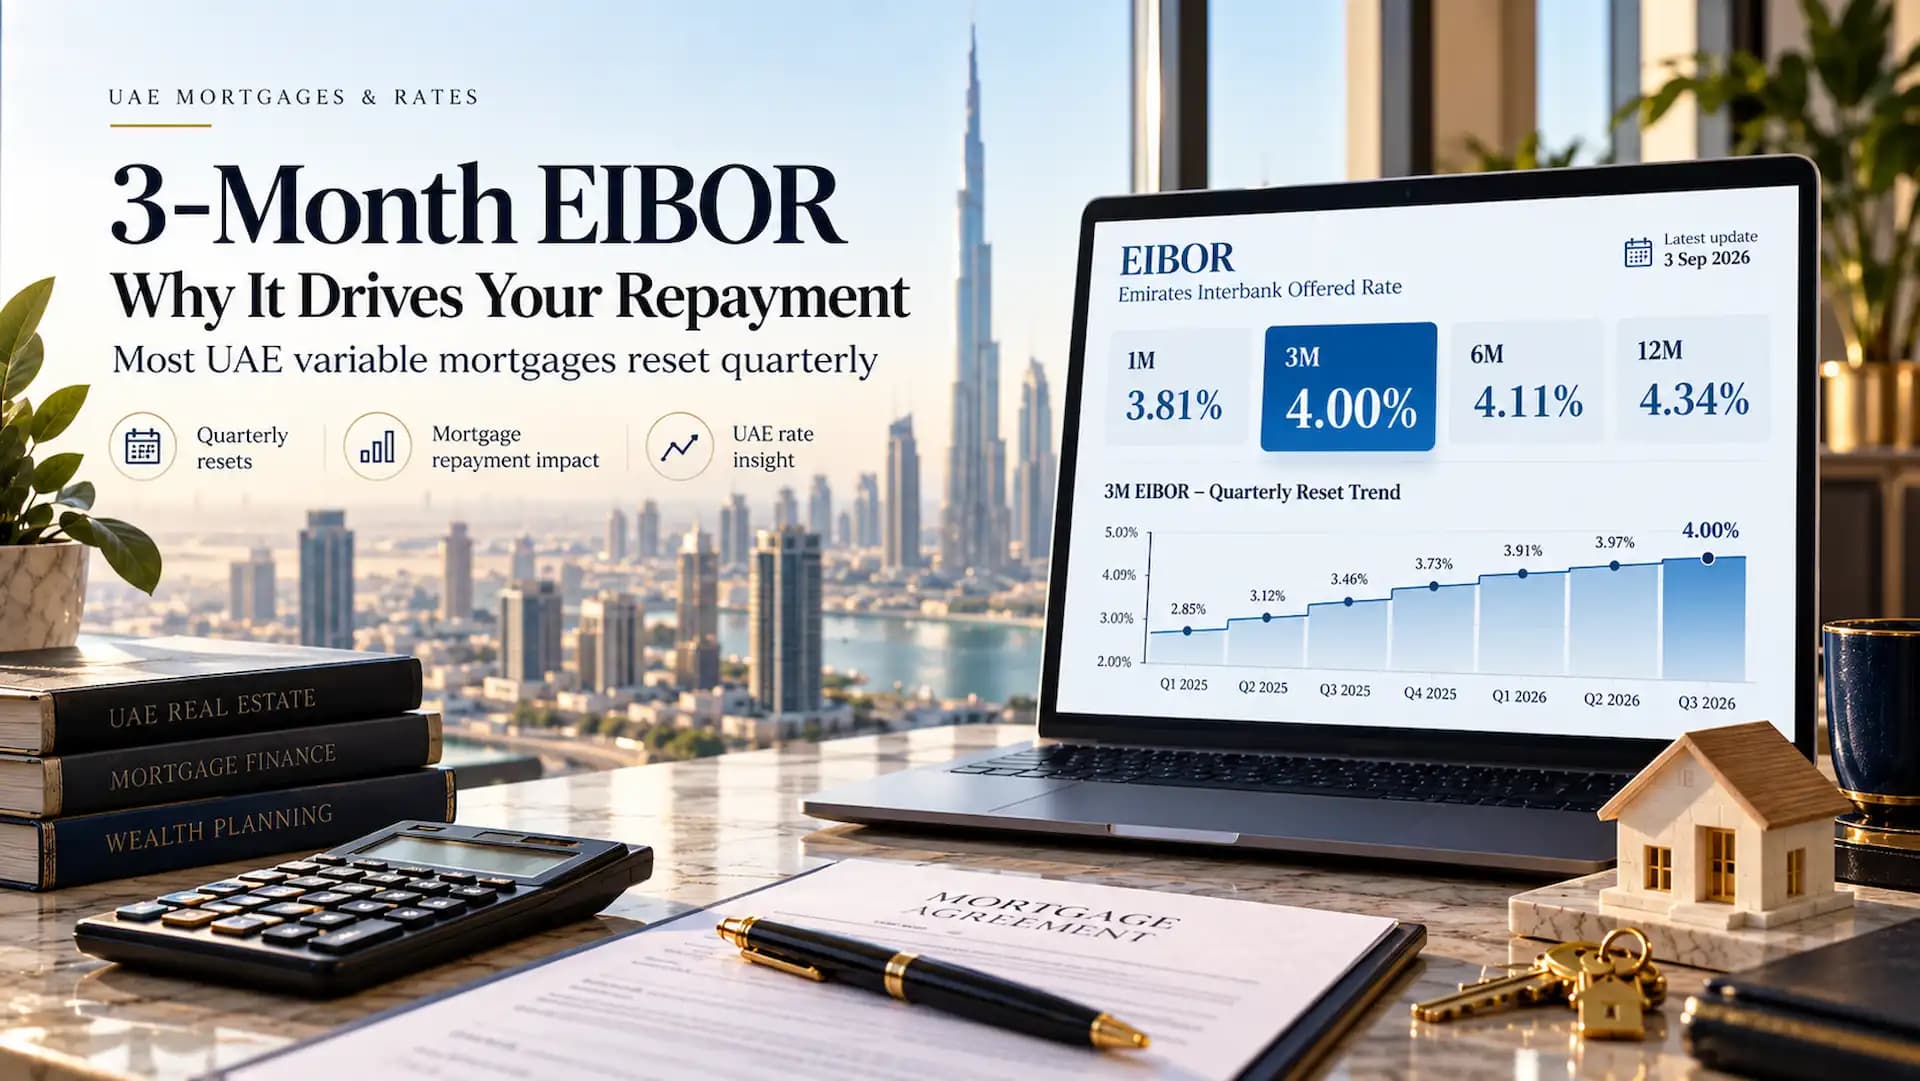
4.00% at the 3 September 2026 CBUAE fixing. One caveat that matters right now: the Central Bank raised its Base Rate by 25 basis points on 17 September 2026, after that fixing. Current three-month EIBOR sits above 4.00%. Check centralbank.ae, or see our EIBOR rate today page for all four tenors.Why three-month became the default
It’s a compromise, and understanding whose compromise tells you what you’re getting. What the bank gets. Three months is long enough that the bank isn’t repricing constantly, and short enough that it isn’t carrying a year of rate risk on money it lent at yesterday’s price. It also matches how banks fund themselves in the interbank market. What you get. Resets frequent enough to capture falls reasonably quickly, spaced enough that you aren’t recalculating every month. Four adjustments a year is legible; twelve is noise. What you give up. Three months of lag in both directions. When rates fall, you wait up to a quarter to feel it. When they rise, you get up to a quarter of grace — and then the full move lands at once. That last point is the whole story of payment shock.How a quarterly reset actually works
Three dates govern it, and people routinely confuse them. Your reset date. Fixed at origination, usually falling quarterly from your drawdown date. On that day your rate recalculates to the prevailing three-month EIBOR plus your margin. The value date. EIBOR fixings apply on a T+2 basis — a rate published on the 1st takes effect on the 3rd. So the fixing that governs your reset is the one whose value date matches your reset date, not the one published that morning. This is the single most common reason a borrower thinks their bank used the wrong number. The period in between. Your rate is frozen. Whatever EIBOR does over the following three months is irrelevant to you until the next reset. A borrower who resets in early September and one who resets in late September can pay different rates for the same product through the same quarter, purely on timing. Worth knowing how the number itself is produced: a panel of UAE banks submits daily, the outliers at both ends are discarded, and a mean is taken of the rest. Our guide to what EIBOR is and how it works covers the methodology.Payment shock: what 2022 did to quarterly-reset borrowers
The best illustration available, because it actually happened. Three-month EIBOR was 0.56% in March 2022. By December it was above 4%. Over the same period the Central Bank lifted its base rate from 1.5% to 4.4%, mirroring eleven Fed hikes. Here’s what that did to someone holding AED 1,500,000 over 25 years at EIBOR + 1.75%, resetting quarterly. Intermediate points are interpolated between the two confirmed anchors, so treat the shape as accurate and the individual steps as indicative:| Reset | 3M EIBOR | Your rate | Monthly payment | Change |
| Mar 2022 | 0.56% | 2.31% | AED 6,587 | — |
| Jun 2022 | ~1.50% | 3.25% | AED 7,310 | +AED 723 |
| Sep 2022 | ~3.00% | 4.75% | AED 8,552 | +AED 1,242 |
| Dec 2022 | ~4.20% | 5.95% | AED 9,619 | +AED 1,067 |
Why it felt worse than the numbers suggest
Three things compounded it. It arrived in steps. A gradual climb would have allowed gradual adjustment. Instead each quarter brought a single, large, non-negotiable increase. Nobody was stress-tested for it. A borrower who took that loan in 2021 was assessed against a rate two to four points above roughly 2%. Reality overshot the test. It was invisible until it wasn’t. Rates were rising all year, but a quarterly-reset borrower’s payment didn’t move until their reset date. The news and the bank statement were three months out of step.How far can a single reset move you?
The useful question if you’re on variable now, or reverting soon. AED 1,500,000 over 25 years, margin 1.75%, starting from EIBOR at 4.00%:| EIBOR move at reset | New payment | Monthly change | Annual cost |
| +0.25 pp | AED 9,665 | +AED 228 | +AED 2,735 |
| +0.50 pp | AED 9,895 | +AED 458 | +AED 5,501 |
| +0.75 pp | AED 10,128 | +AED 692 | +AED 8,298 |
| +1.00 pp | AED 10,364 | +AED 927 | +AED 11,125 |
Choosing your tenor
Most borrowers never realise this is a choice. Some banks offer alternatives at origination, and the difference is real. One-month. Fastest transmission in both directions. Suits someone who believes rates are falling and wants to capture it quickly, and who can absorb twelve adjustments a year. Three-month. The default. Reasonable balance of responsiveness and stability, and the deepest market, which usually means the sharpest margins. Six-month. Slower, smoother. Two adjustments a year. Useful if predictability matters more than capturing every move. Twelve-month. Maximum insulation. One reset a year, so a rising market takes up to twelve months to reach you. Prices highest, because the bank carries the risk for longer.The trade-off in one line
Shorter tenors are cheaper today and more volatile. Longer tenors cost more today and move less. In a rising market longer is protection; in a falling market it’s a delay.Can you change it?
Rarely within an existing facility — the tenor is written into your loan agreement. What you can do is choose it at origination if your lender offers options, or change it by refinancing. If your fixed period is ending, that’s the natural moment to revisit both the tenor and the margin. Our guides to refinancing and mortgage buyout cover the economics, and no 4% transfer fee applies on a switch because the property doesn’t change hands.Managing your reset
- Find your reset date and diary it. It’s in your loan agreement. Knowing it turns a surprise into a plan.
- Check the fixing a few days before, allowing for the T+2 value date.
- Keep a buffer sized to one full move. Roughly AED 230 per AED 1.5 million per 25 basis points is a reasonable rule of thumb.
- Watch the Fed, not local commentary. The dirham is pegged to the dollar, so UAE rates follow FOMC decisions with a lag of roughly one to two months. The Fed calendar is your early warning.
- Reconcile once a year. Take your reset date, find the fixing with the matching value date, add your margin, and compare against your statement. Discrepancies are usually a value-date misunderstanding, but occasionally a reset applied a cycle late.
- Know your margin. EIBOR is identical for everyone. Your margin is set once, at origination, and typically runs 0.70% to 2.25%. Over twenty-five years it matters far more than any individual fixing. Our guide to current UAE mortgage rates shows where margins currently sit.