Home Loan Pre-Approval in Dubai: Process & Timeline

Mortgage5 min read· 12 Sept 2026
Home Loan Pre-Approval in Dubai
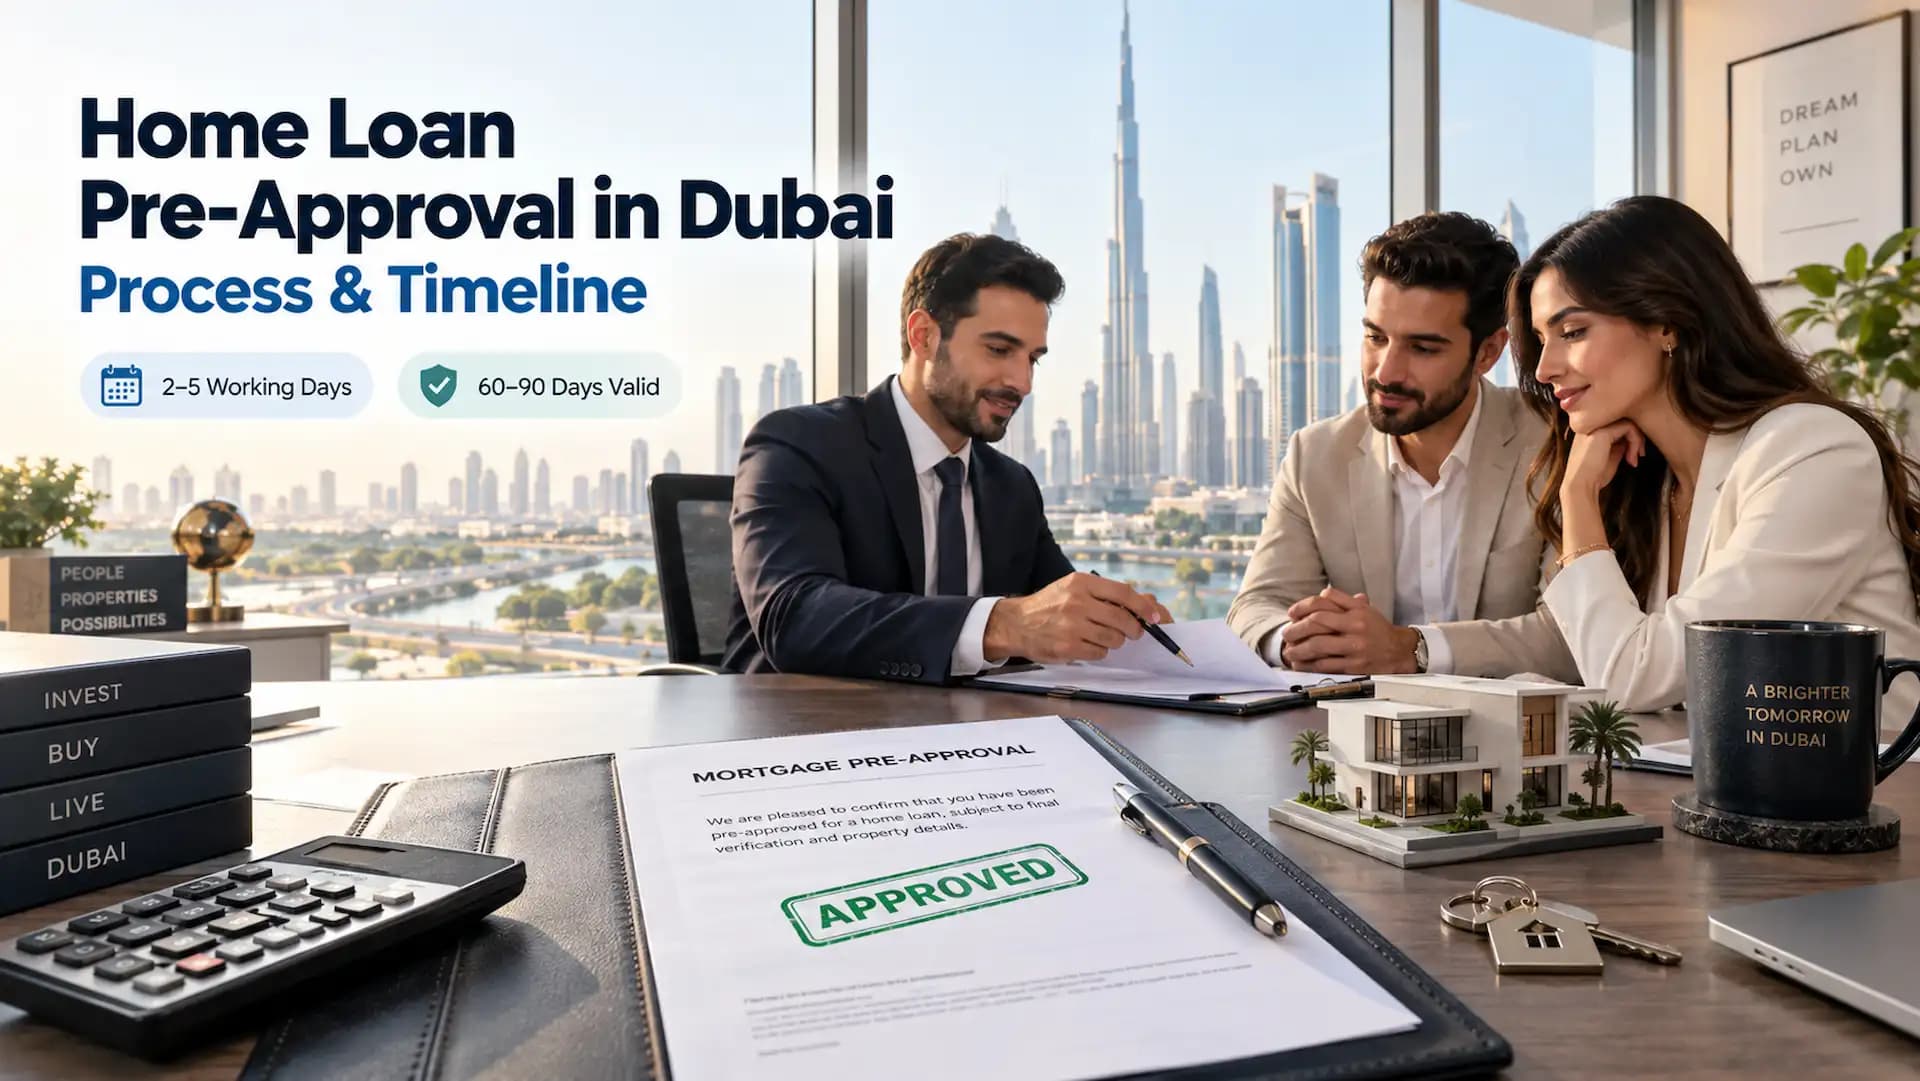
Pre-approval takes two to five working days, costs nothing at most UAE banks, and gives you a written statement of what a lender is willing to put behind you. Most letters stay valid for 60 to 90 days. It’s the step that turns you from someone scrolling listings into someone who can actually make an offer, and it’s also the step people most often skip. Agents in Dubai have stopped taking unfinanced offers seriously, and a seller has no reason to hold a property for a buyer who hasn’t shown they can complete. What follows is how the process runs, what the bank is weighing up while it runs, and what can still change between your letter arriving and the money actually landing.

The short version

How long it takes 2–5 working days
What it costs Nothing at most banks
How long it lasts 60–90 days, occasionally 30
What it’s based on You, not a specific property
Does it lock your rate? No
Does it guarantee the loan? No

What pre-approval actually is

It’s a written, conditional statement from a UAE-licensed bank confirming it’s willing to lend you a specific amount, based on a preliminary look at your finances. Crucially, it assesses you rather than any particular property.

The names it goes by

You’ll see the same thing called approval in principle, in-principle approval, AIP, or decision in principle. Some banks use “pre-approval” for a lighter check and keep “approval in principle” for a fuller one, but there’s no industry-wide convention, so it’s worth asking what’s actually behind the letter rather than reading anything into the label.

What the letter contains

A proper pre-approval letter gives you a maximum loan amount, an indicative rate, the term, and a validity date, along with any conditions the bank still needs satisfied. Pay attention to that word “indicative” on the rate. Pre-approval does not lock your interest rate — that gets confirmed at final offer, and it can move in between, particularly if EIBOR shifts while you’re still viewing properties. Our comparison of fixed versus variable mortgages covers which structure shelters you from that and which doesn’t.

How it differs from pre-qualification

Pre-qualification is an estimate built on figures you’ve told someone, with no documents verified and no credit check behind it. It costs nothing and it’s worth about the same. Pre-approval involves real document checks, a credit bureau pull, liability verification and a formal affordability assessment. When an agent asks whether you’re pre-approved, this is the thing they mean.

Why it’s worth doing before you start viewing

Three reasons, and the third is the one people underestimate. You get a real budget. Not what a calculator suggested or what you hope you can afford, but a figure a bank has looked at your file and agreed to. Most people find that number differs from their estimate in one direction or the other, and it’s much better to know now. You become a credible buyer. In a market where sellers regularly field several offers, a pre-approval letter is the difference between an offer that gets considered and one that gets politely parked. Some agents won’t arrange viewings without one. You find out what’s wrong while it’s still cheap to fix. This is the real value. If your debt burden ratio is too high or there’s something ugly on your credit file, discovering it during pre-approval costs you a fortnight and some admin. Discovering it after you’ve signed Form F and handed over a 10% deposit costs considerably more, and by then the clock is running on a contract.

What the bank is assessing

Your credit file

Every UAE bank pulls your Al Etihad Credit Bureau report as a mandatory step. It shows every active and closed facility, up to 36 months of payment history, bounced cheques and court judgments. There’s no published universal minimum score, though most lenders want a clean report and approval odds improve noticeably above 650 to 700. Below roughly 580 it gets difficult almost everywhere. The 580 to 680 band is where bank policies diverge most sharply, which is precisely where knowing the panel earns its keep. We’ve covered how to check your credit score and what score you actually need separately. Pull your own report before you apply. Checking it yourself is a soft enquiry with no effect on your score, and finding a forgotten liability yourself is a great deal more comfortable than having an underwriter find it for you.

Your debt burden ratio

The Central Bank caps total monthly debt repayments, the new mortgage included, at 50% of gross income. This is the limit that sets most pre-approval amounts, and the detail that catches people out is credit cards, because banks count around 5% of your total limits as a monthly commitment whether you’ve ever used them or not. When a pre-approval comes back smaller than someone expected, this is almost always the reason. Our guide to how DBR works and how to bring it down sets out what to cut and in what order, and it really is worth doing beforehand rather than afterwards.

Employment and income stability

Most lenders want three to six months with your current employer if you’re salaried. Probation is usually a problem, though a few banks will look at it depending on who you work for. Self-employed applicants generally need two years of trading history, and banks apply an income haircut of 20% to 40% to business earnings before the affordability sum even begins. That haircut, rather than the earnings themselves, is why so many profitable business owners open the letter and find a disappointing number staring back. Frequent job changes read badly too, even when every move was a promotion.

What you’ll need to submit

If you’re salaried

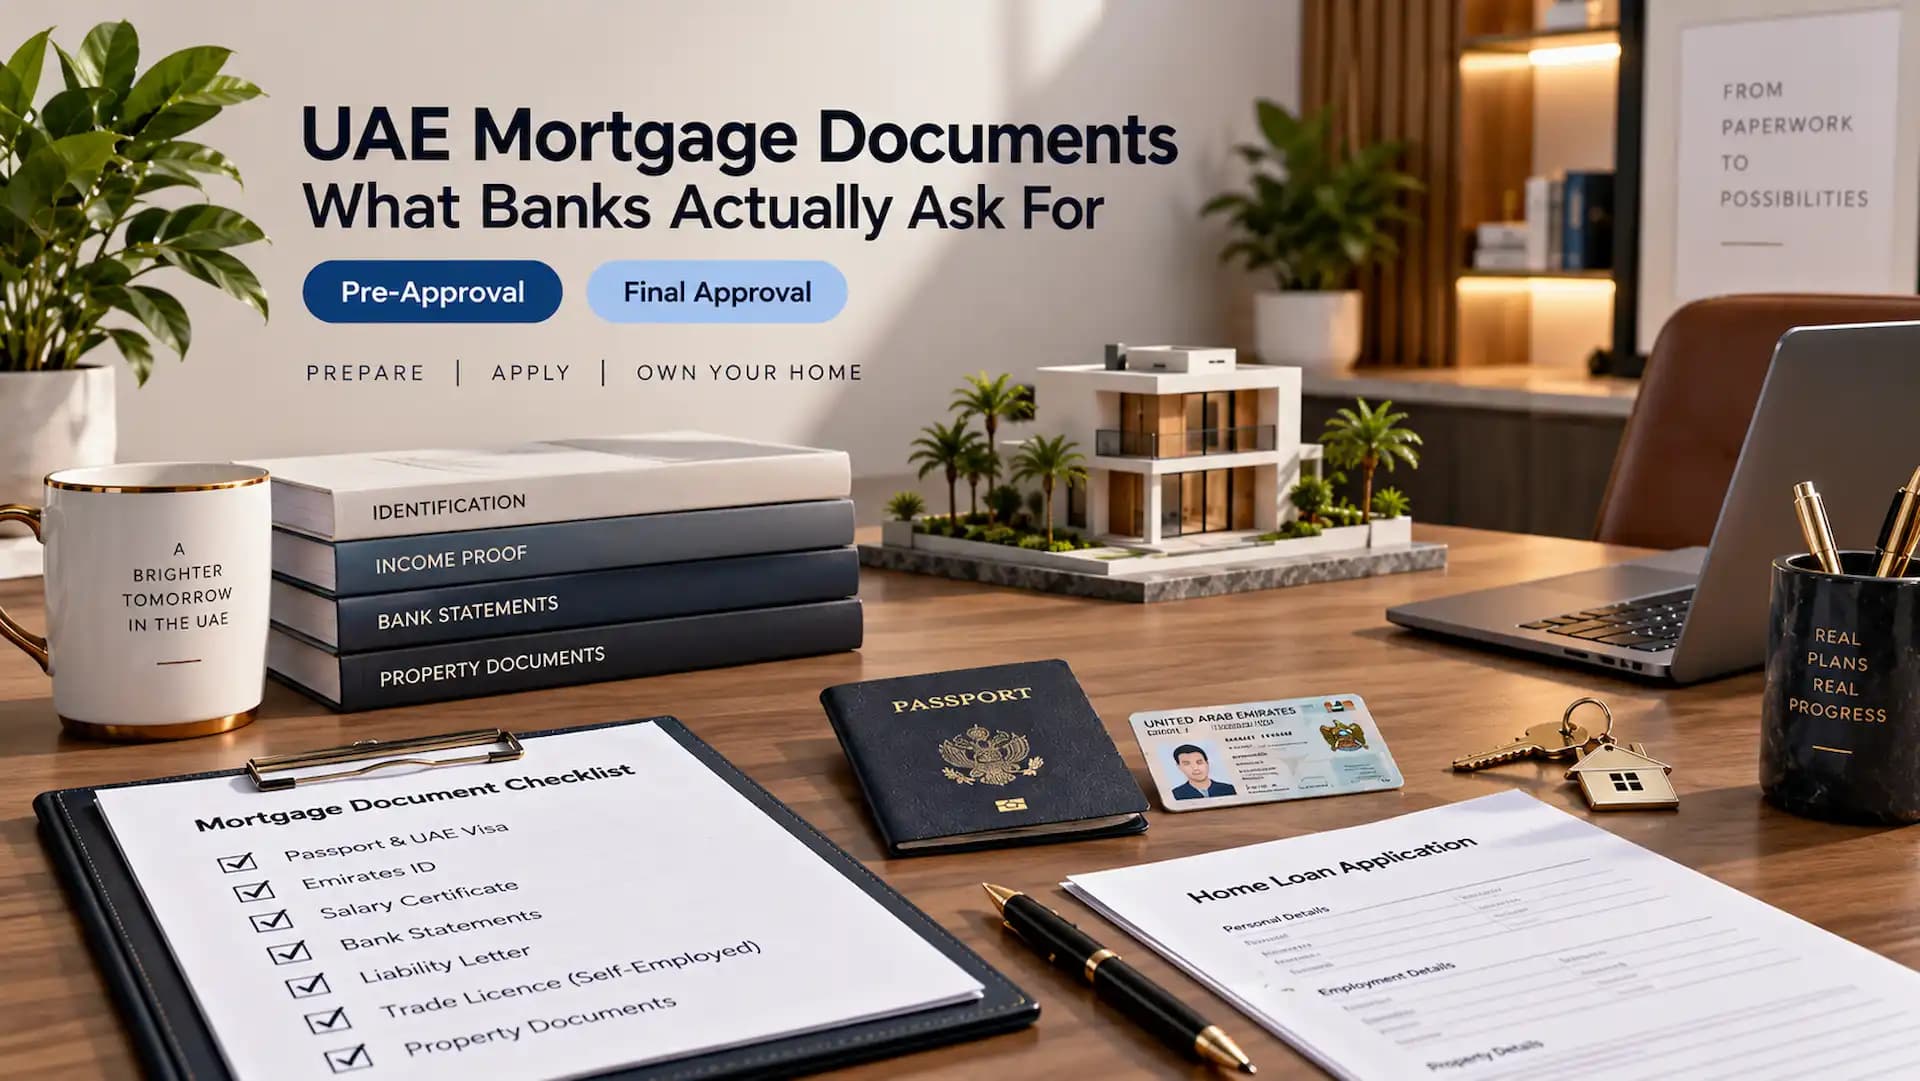
Passport, visa and Emirates ID, a salary certificate, three to six months of personal bank statements, and a list of your existing liabilities.

If you’re self-employed

Everything above, plus a valid trade licence with at least two years of history, your memorandum of association, two years of audited financials, and twelve months of company bank statements.

If you’re buying from overseas

Passport, six months of overseas bank statements, proof of income in your home country, and a credit report from where you live. Expect more documentation and a longer assessment, since your liabilities won’t appear on an AECB report and the burden of evidence therefore sits with you. Only a handful of UAE banks actively underwrite overseas income, so lender choice matters more here than anywhere else. Our non-resident finance page covers who lends and on what terms, with more detail in our guide to getting a Dubai mortgage as a non-resident.

Declare the awkward things yourself

If there’s a bounced cheque or a missed payment in your history, say so upfront. Three years on, most of it is survivable and perfectly manageable in context. The same fact discovered on the report after you’ve said nothing reads as concealment, and that changes how the rest of your file gets read.

Timing, cost and validity

How long it takes

Two to five working days once your documents are complete. You’ll see three to seven quoted elsewhere, which is usually the same process with a slow document-gathering phase bolted onto the front. What actually stretches the timeline is incomplete paperwork, and liability letters from your existing lenders are the usual culprit. Request those first, not last.

What it costs

Nothing at most UAE banks. A small number charge a non-refundable application fee, so it’s worth confirming before you submit. Pre-approval being free doesn’t make the mortgage free, of course — valuation, arrangement fees and insurance all arrive later.

How long the letter lasts

Most run 60 to 90 days, some 30. Treat that date as your active search window and time the application accordingly. Apply too early and it lapses mid-search; too late and you’re negotiating without it.

Renewing an expired letter

Usually straightforward with updated bank statements and payslips, and with the same bank and unchanged circumstances it can take a day or two. It isn’t automatic though, and it certainly doesn’t guarantee the same number. A job change, a new car loan, a shift in the bank’s lending policy or a move in rates can all produce a smaller figure second time round, even when nothing about your situation feels any different to you.

Does applying hurt your credit score?

You’ll find confident answers in both directions on this, and the accurate picture sits between them.

Soft enquiries versus hard enquiries

Checking your own report is a soft enquiry and has no effect on your score at all, so check it as often as you like. A lender pulling your report during an application is a hard enquiry, and hard enquiries are one of the factors the AECB scoring model takes into account. A cluster of recent applications can pull your score down temporarily.

The rate-shopping window

Mortgages get special treatment, though. The AECB operates a rate-shopping window under which multiple hard enquiries for the same kind of borrowing, made within a short period, are grouped and treated as a single enquiry. Mortgages, car loans and student loans all qualify, on the sensible reasoning that anyone borrowing that much will shop around. The exact length of that window isn’t officially published. Banking analysts have estimated somewhere between 14 and 45 days, so treat it as a guide rather than a rule you can plan to the day. In practice that means comparing several lenders inside a tight timeframe is largely protected, and you should do it. Spreading applications across three months isn’t protected, and neither is applying for a credit card or a car loan in the middle of your mortgage search.

The part that isn’t about your score

There’s a second effect worth understanding, and it operates entirely separately. Underwriters read application patterns directly off the report, and a run of recent applications makes a lender cautious whatever the score happens to say. No rate-shopping window protects you from a human being forming an impression of your file. This is one of the quieter arguments for going through a broker. A single submission placed strategically across a panel generates fewer enquiries than approaching six banks yourself, and it avoids creating the pattern that makes underwriters uneasy in the first place. We’ve written more on using a broker versus going direct.

From pre-approval to final approval

Your pre-approval isn’t the loan. Final approval comes once you’ve chosen a property, and it brings in everything the bank couldn’t assess at the earlier stage.

What can still change the answer

The valuation. The bank commissions an independent valuation and lends against the lower of the purchase price and that figure. Come in AED 100,000 under, and the loan drops while your cash requirement rises to cover the gap. The property itself. Not every unit is financeable. Buildings carrying significant service charge arrears, unusual layouts, very small studios and projects sitting on a lender’s non-approved list can all fail here even when you sailed through personally. Your circumstances. Pre-approval is conditional on your position holding steady. Change jobs, take on new debt or see your income drop, and the bank can revisit, and will. Legal checks. Title verification and encumbrance checks happen at final approval, not before it.

What not to do while you’re searching

Don’t change jobs. Don’t take out a car loan. Don’t open a new credit card, however good the airline miles look. Don’t move large unexplained sums in or out of the account the bank is reviewing, and don’t let any existing payment slip. Each of these can shrink or void a pre-approval you’re already holding, and we’ve watched every one of them cost somebody a deal at least once.

Why pre-approvals get declined

DBR too high. The most common reason by a distance, and usually fixable by clearing liabilities or cutting card limits before you go again. Credit file problems. Late payments, defaults or bounced cheques. Some age out on their own, some need addressing directly. Not enough employment history. Probation, under three months in a role, or a pattern of frequent moves. Income below the threshold. Most banks set a minimum somewhere around AED 10,000 to 15,000 a month for salaried applicants, higher for self-employed. Documentation gaps. Incomplete or inconsistent paperwork, which of everything on this list is the most avoidable. A decline is rarely permanent. It’s a snapshot of how your file happened to look on the day you submitted it, and most of what causes one can be changed. Our breakdown of why Dubai mortgages get rejected goes through the patterns, and there’s a worked case study on turning a rejection into an approval. The one thing not to do is immediately fire off an application somewhere else, which addresses nothing and adds another enquiry to the pile.

Getting pre-approved

The genuinely useful thing about pre-approval is that it surfaces problems while they’re still cheap. A DBR issue found now costs you two weeks and some admin. The same issue found after you’ve signed and paid a deposit costs a great deal more, and by then you’re working against a contractual deadline. We submit across 15+ UAE lenders and we’ll tell you plainly what your file will do, including what to clear first if today’s number isn’t the one you were hoping for. Get pre-approved, or talk to a consultant if you’d rather think it through first. Once your letter’s in hand, our guide to getting a mortgage in Dubai covers everything that happens next, and you can sanity-check the numbers on the eligibility calculator or the mortgage calculator.

Frequently asked questions

How long does mortgage pre-approval take in Dubai? Two to five working days once your documents are complete. Delays nearly always come from missing paperwork rather than the bank’s assessment. Does pre-approval cost anything? Nothing at most UAE banks. A small number charge a non-refundable application fee, so confirm before you submit. How long is a pre-approval valid? Usually 60 to 90 days, occasionally 30. Renewal is normally straightforward with updated statements but isn’t guaranteed to produce the same amount. Does pre-approval guarantee I’ll get the mortgage? No. It’s conditional. Final approval depends on the property valuation, legal checks, and your circumstances staying as they were. Does applying for pre-approval hurt my credit score? Checking your own report doesn’t. A lender’s check is a hard enquiry and does count as a scoring factor, but the AECB groups multiple mortgage enquiries made within a short shopping window as one, so comparing lenders in a tight timeframe is largely protected. Can I get pre-approved by more than one bank? Yes, and comparing offers is sensible. Keep the applications close together rather than spread over months, and bear in mind underwriters read application patterns separately from the score. Does pre-approval lock in my interest rate? No. The rate shown is indicative and gets confirmed at final offer, so it can move while you’re searching. Can non-residents get pre-approved? Yes, from a smaller pool of lenders, typically at 50% to 65% LTV and with heavier documentation.