Two insurance policies are mandatory on every UAE mortgage. Most borrowers accept whichever the bank puts in front of them at signing, because by that stage the paperwork is nearly done and the premium looks small.
Across twenty-five years it isn’t small. On a AED 1.5 million loan, the difference between a competitive life premium and an uncompetitive one is roughly AED 68,000 — more than most people negotiate off the interest rate.
Both apply to residents and non-residents, and to conventional and Islamic facilities alike. Neither is optional, and neither can be added later — both must be in place before the bank disburses.
The spread between the best and worst end of that range is AED 113,743. Even the gap between 0.30% and 0.60% is AED 68,246.
That is the single largest negotiable cost in a UAE mortgage after the interest margin, and almost nobody treats it as negotiable.
Ask for the specific requirement in writing before you shop around. A policy that doesn’t meet the bank’s minimum gets rejected, and you’ll have paid for underwriting twice.
First, a term that confuses expats
If you’ve bought property in Australia, New Zealand, Canada or the UK, you’ll know Lenders Mortgage Insurance — a premium the borrower pays to protect the lender against default, usually triggered above 80% LTV. The UAE doesn’t have that. There is no LMI product here and no default-protection premium. Instead the Central Bank controls lender risk through hard loan-to-value caps, so a bank simply lends less rather than insuring the excess. What the UAE requires is different: life cover and property cover. Both protect the loan, but against death and physical damage rather than default.The two mandatory policies
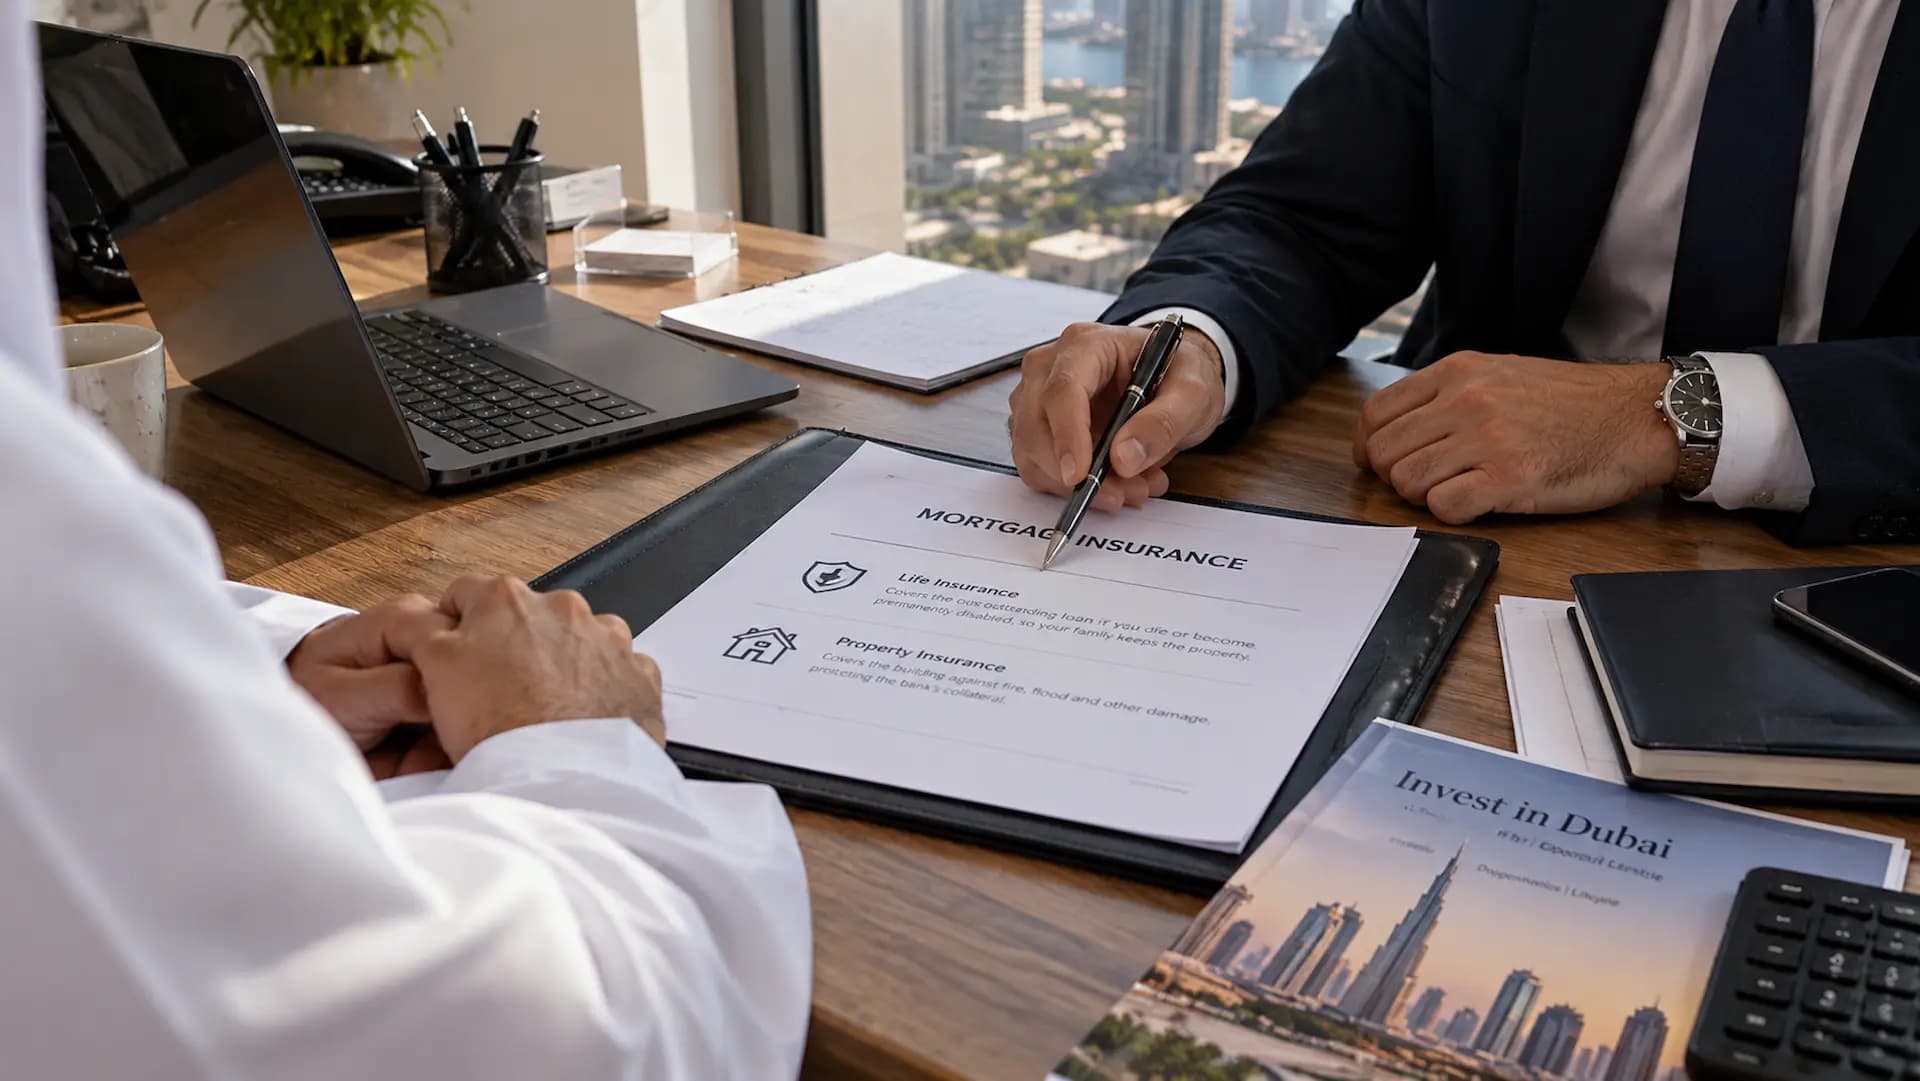
| Mortgage life insurance | Property insurance | |
| Covers | The outstanding loan if you die or become permanently disabled | The building against fire, flood and damage |
| Protects | Your family’s equity, and the bank’s repayment | The bank’s collateral |
| Typical cost | 0.3%–0.8% of the declining balance per year | 0.05%–0.10% of property value per year |
| Mandatory? | Yes, every UAE lender | Yes, every UAE lender |
Mortgage life insurance
Also called decreasing term assurance or mortgage protection insurance. If you die or become totally and permanently disabled during the term, it clears the outstanding balance so your family keeps the property rather than inheriting the debt.Decreasing term versus level term
The default is decreasing term: the cover falls in step with your balance, so it always pays roughly what’s owed and nothing more. It’s the cheaper option and it’s what banks bundle. Level term keeps the sum insured constant for the whole period. It costs more, and the reason it’s worth considering is rarely explained: after ten years your balance has fallen substantially, but a level policy still pays the original sum. Your family would receive the property and the difference. For a borrower with dependants and no other life cover, that gap can be worth considerably more than the extra premium. For someone with separate family protection already in place, decreasing term is the sensible choice.What it costs
Premiums typically run 0.3% to 0.8% of the declining balance per year, depending on your age, health, smoking status, the sum insured and the policy type. On a AED 1.5 million loan over 25 years at 4.25%:| Annual rate | Year 1 | Year 10 | Total over 25 years |
| 0.30% | AED 4,500 | AED 3,392 | AED 68,246 |
| 0.40% | AED 6,000 | AED 4,523 | AED 90,994 |
| 0.60% | AED 9,000 | AED 6,784 | AED 136,492 |
| 0.80% | AED 12,000 | AED 9,045 | AED 181,989 |
Property insurance
Covers the physical structure against fire, flood, escape of water and similar perils. It protects the bank’s collateral rather than your contents, which you’d insure separately. Cheaper and less variable: roughly 0.05% to 0.10% of property value annually. On a AED 1,875,000 property that’s AED 938 to AED 1,875 a year, or AED 23,000 to AED 47,000 across the term. Worth checking what sum insured your bank requires. Standard practice is the reinstatement value or the mortgage balance, whichever is higher, but some banks require 110% to 120% of the mortgage balance, which raises the premium.The bank’s policy versus your own
This is where the money is.How the bank’s group policy works
Banks bundle a group life policy covering all their mortgage borrowers at a flat group rate with no individual underwriting. It’s fast, it’s administratively simple, and the bank’s team already knows the paperwork — which genuinely speeds approval. But a group rate is an average across everyone in the pool. Younger, healthier borrowers are subsidising older and less healthy ones.When your own policy wins
You can buy an individual term policy from a UAE-licensed insurer and assign it to the bank. You go through underwriting and get a rate priced to your risk rather than the pool’s. If you’re young, healthy and a non-smoker, that is frequently and significantly cheaper. Standard life cover can start from around AED 50 a month for AED 1 million of cover for a good-risk applicant. If you’re older, a smoker, or have a medical history, the group rate may well be better — because the pool is subsidising you.The trade-off
An external policy means underwriting, which takes time and may require a medical. It adds an administrative step to an application already running against a Form F deadline. The sensible approach is to get a quote early, before you’re at the signing stage with no time to arrange an alternative. At that point the bank’s policy is the only realistic option and you’ve lost the choice.Assignment, and the trap at refinance
Whichever route you take, the policy must be formally assigned to the lender for the life of the mortgage. The bank becomes beneficiary to the extent of the outstanding balance; anything above that goes to your named beneficiaries. Here’s the part people discover at the wrong moment: the assignment does not automatically transfer when you refinance. Switch lenders and your existing insurer has to reassign the policy to the new bank, or the new bank will require a fresh policy through its own panel. If you’ve aged five years or your health has changed since the original underwriting, that new policy may cost materially more. Raise it at the start of any refinance conversation rather than discovering it two weeks before completion. Our guides to refinancing and mortgage buyout cover the wider economics of switching.What banks actually require
Requirements vary more than people expect, and they affect your premium:| Requirement | Standard | Variations |
| Life cover amount | Outstanding balance | Some require balance plus one year’s interest |
| Property sum insured | Reinstatement value or balance, whichever higher | Some require 110%–120% of balance |
| Provider | Any UAE-licensed insurer | Some mandate in-house or panel insurers |