Every UAE mortgage offer leads with a rate, and almost every buyer compares offers by that rate alone. It is the wrong number to compare.
The headline rate on a UAE home loan is an introductory rate that lasts two, three or five years. What follows it — EIBOR plus a fixed margin — runs for the other twenty-odd years, and that is where most of your interest is paid. Add a processing fee that may or may not exist, and two offers that look a quarter-point apart can be AED 180,000 apart over the life of the loan, sometimes in the opposite direction from the one their headlines suggest.
This guide puts a dirham figure on a rate, then shows how to compare offers the way the bank prices them. Every example uses a AED 1.5 million mortgage over 25 years, with three-month EIBOR at 4.3704% as fixed on 9 October 2026 and the Central Bank’s Base Rate at 3.90%.
The rule of thumb that falls out of this: on a AED 1.5 million loan, every 0.25 percentage points is worth about AED 200 a month and AED 60,000 over 25 years. Scale it to your own balance — on AED 3 million, double both figures; on AED 750,000, halve them.
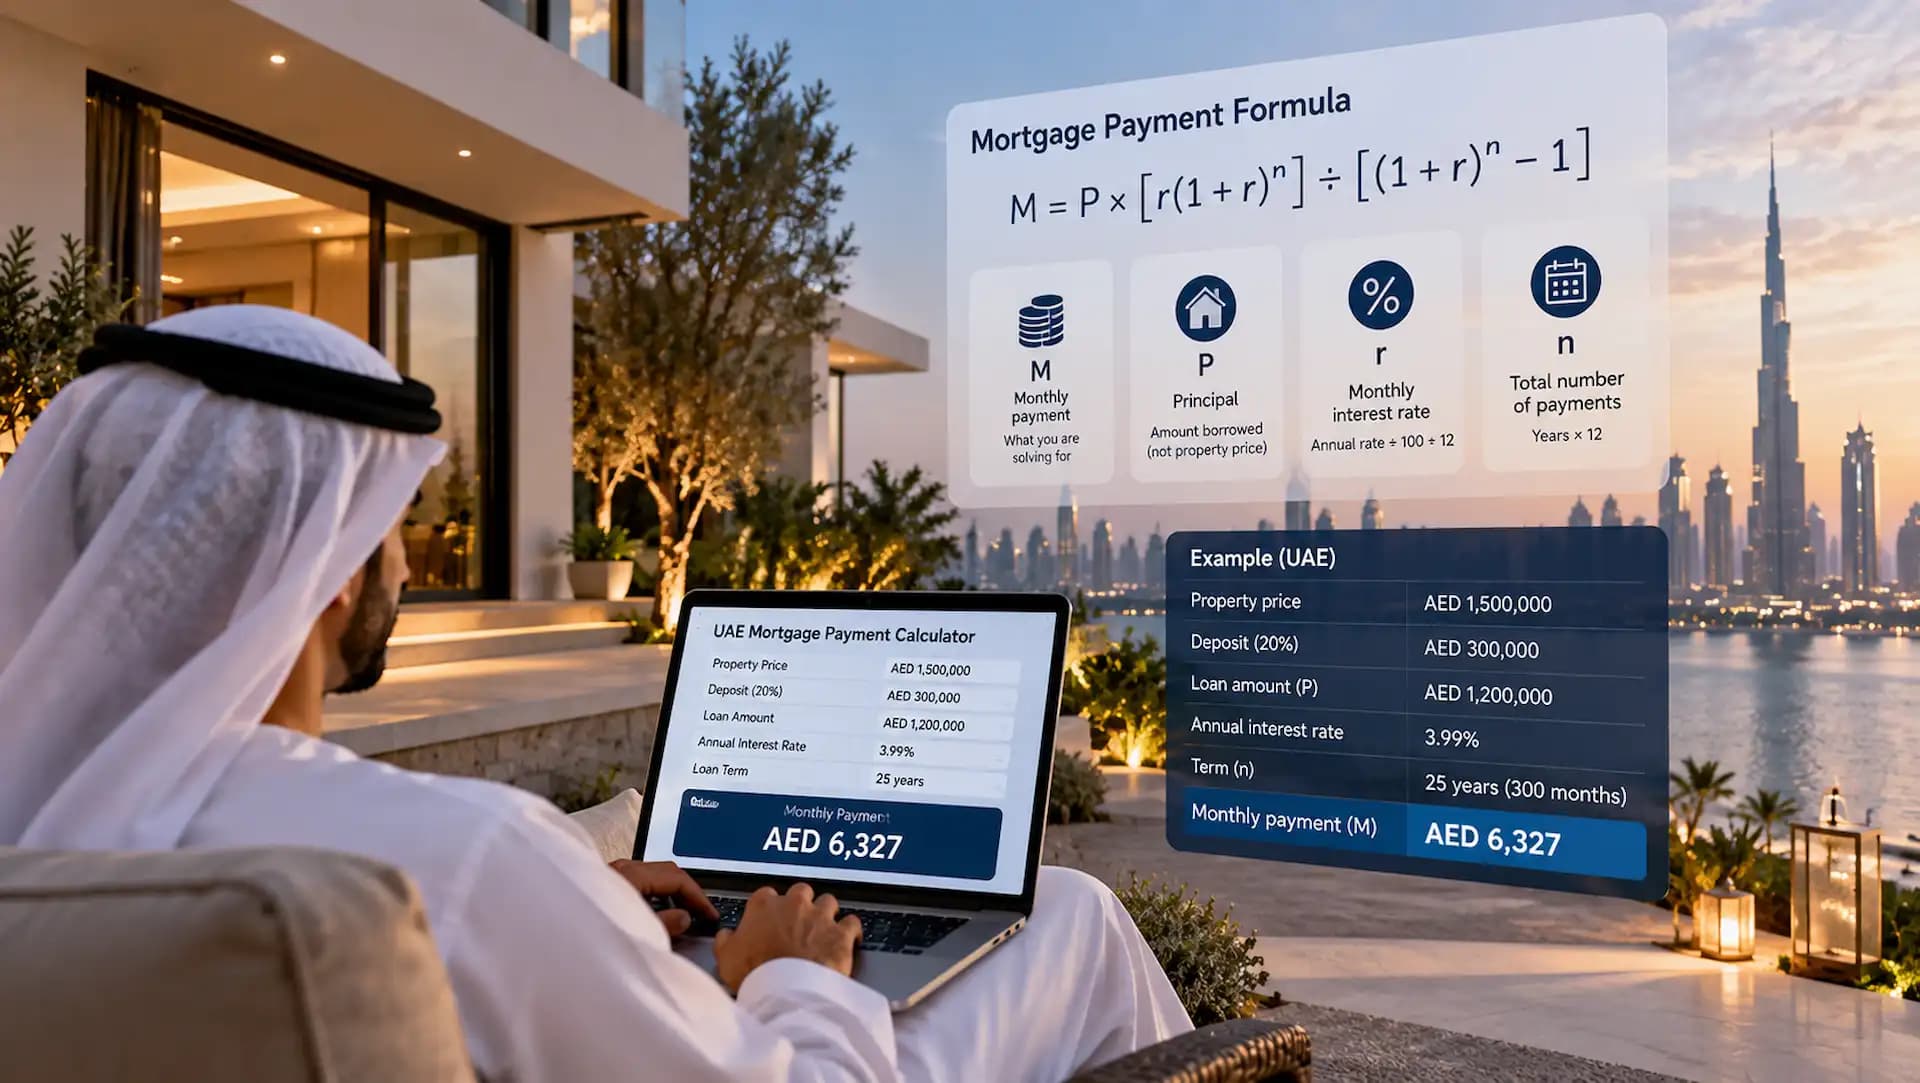
That table assumes the same rate for 25 years, which no UAE mortgage actually has. It is useful for one thing: knowing what a quarter-point is worth when someone tells you it does not matter. If you want the formula that sits behind it, it is set out step by step in how to calculate mortgage payments in the UAE.
After the reset, Offer A’s payment is AED 9,757 a month and Offer B’s is AED 9,002 — a gap of AED 755 a month that runs for twenty-two years. Offer B overtakes in month 58, under five years in.
Here is the part most people do not expect: that break-even point barely moves whatever EIBOR does. Run the same comparison with EIBOR a full point lower or a full point higher, and B still wins from year five and by between AED 175,000 and AED 191,000 over the term. EIBOR moves both loans together. The margin is the only thing that separates them permanently.
So the question to ask about any offer is not “what is the rate?” but “what is the margin, and how long will I keep this loan?”
Each 25 basis point move in EIBOR is worth about AED 205 a month at this balance. The Central Bank’s Base Rate went up 25 basis points on 17 September 2026, following the US Federal Reserve because the dirham is pegged to the dollar, and three-month EIBOR rose with it. Anyone already on a variable rate felt that within one reset cycle.
The +2.00 line is worth noticing. That is roughly the stressed rate your bank tests you at before approving the loan, and it is AED 1,700 a month above today’s figure. If that number does not fit your budget, it will not fit the bank’s affordability test either — your debt burden ratio is calculated against it. How the benchmark itself is set is explained in EIBOR and how it affects your mortgage.
The shorter you hold the loan, the more the fee weighs. Over a three-year fixed period — the point at which many borrowers refinance — a AED 10,500 fee adds more than a quarter-point to the real cost.
That has a direct consequence. A 3.79% offer with a AED 10,500 fee is more expensive than a 3.99% offer with no fee if you switch after three years — an effective 4.05% against 3.99%. Hold it ten years and the order reverses: the 3.79% loan works out at about 3.89%. The right choice depends on the same question as before: how long will you keep the loan?
A 3.5% flat personal loan costs more than a 6.5% mortgage. Never compare a flat rate with a mortgage rate, and if a personal loan offer does not state its reducing-balance or annualised rate, ask for it in writing before you sign.
What a rate is worth in dirhams
Start with the plain question: what does each step in the rate cost?| Rate | Monthly payment | Difference vs 4.00% | Total interest, 25 years | Difference vs 4.00% |
| 3.50% | AED 7,509 | −AED 408 | AED 752,806 | −AED 122,460 |
| 3.75% | AED 7,712 | −AED 206 | AED 813,590 | −AED 61,675 |
| 4.00% | AED 7,918 | — | AED 875,266 | — |
| 4.25% | AED 8,126 | +AED 209 | AED 937,821 | +AED 62,556 |
| 4.50% | AED 8,337 | +AED 420 | AED 1,001,246 | +AED 125,980 |
| 5.00% | AED 8,769 | +AED 851 | AED 1,130,655 | +AED 255,389 |
| 5.50% | AED 9,211 | +AED 1,294 | AED 1,263,394 | +AED 388,128 |
| 6.00% | AED 9,665 | +AED 1,747 | AED 1,399,356 | +AED 524,091 |
Every UAE mortgage has two rates
A UAE offer is built from two parts:- The introductory rate. Fixed for a set period — commonly two, three or five years. This is the headline.
- The reversion rate. What applies for the rest of the term: a benchmark, usually one- or three-month EIBOR, plus a margin that is fixed in your contract for the life of the loan.
The comparison that changes decisions
Take two real-world shaped offers on the same AED 1.5 million loan:- Offer A — 3.75% fixed for three years, then three-month EIBOR + 1.99%
- Offer B — 4.29% fixed for three years, then three-month EIBOR + 1.00%
| Cumulative interest paid | Offer A | Offer B | Difference |
| After 3 years | AED 162,579 | AED 186,487 | A cheaper by AED 23,908 |
| After 5 years | AED 335,079 | AED 332,542 | B cheaper by AED 2,536 |
| After 10 years | AED 727,315 | AED 661,050 | B cheaper by AED 66,265 |
| After 25 years | AED 1,353,606 | AED 1,170,379 | B cheaper by AED 183,227 |
- If you are confident you will sell or refinance within about four years, the lowest introductory rate can win.
- If there is any real chance you hold the loan past year five, the lowest margin almost always wins.
- If the teaser is lower and the margin is lower, you have found the better offer. That is rarer than it should be.
Longer fixes change the arithmetic again
A five-year fix at 4.19%, reverting to EIBOR + 1.50%, costs AED 19,473 more than Offer A over the first three years — and is AED 39,615 cheaper by year five, AED 74,551 cheaper by year ten, and AED 138,483 cheaper over the term. You are paying more early for two more years of certainty and a lower margin afterwards. Whether that certainty is worth it is the subject of fixed versus variable in the UAE.What EIBOR does to your payment after the fix
Once the introductory period ends, your rate moves with the benchmark. Three years into the AED 1.5 million loan at 3.99%, the balance is about AED 1,388,459 with 22 years left. At EIBOR + 1.50%:| Three-month EIBOR moves by | Your rate | Monthly payment |
| −1.00 point | 4.87% | AED 8,580 |
| −0.50 point | 5.37% | AED 8,975 |
| −0.25 point | 5.62% | AED 9,175 |
| No change (4.37%) | 5.87% | AED 9,378 |
| +0.25 point | 6.12% | AED 9,583 |
| +0.50 point | 6.37% | AED 9,791 |
| +1.00 point | 6.87% | AED 10,212 |
| +2.00 points | 7.87% | AED 11,079 |
The fee that hides inside the rate
The second thing a headline rate leaves out is the processing fee. Banks charge anything from nothing to around 1.05% of the loan including VAT — Emirates NBD’s published Key Facts Statement sets it at 1.05% or AED 10,500, whichever is lower. Either way it is money paid up front, which makes the loan more expensive than its rate says. The cleanest way to see that is to convert the fee into an effective rate. On AED 1.5 million at 4.00%:| Processing fee | Effective rate if you keep the loan 3 years | 5 years | 25 years |
| None | 4.00% | 4.00% | 4.00% |
| AED 7,875 (0.5% + VAT) | 4.19% | 4.12% | 4.05% |
| AED 10,500 | 4.26% | 4.17% | 4.07% |
| AED 15,750 (1% + VAT) | 4.39% | 4.25% | 4.10% |
How to compare two offers properly
Put both offers side by side and ask for five numbers each:- The introductory rate and how long it lasts.
- The reversion margin and which EIBOR it tracks. One-month EIBOR resets more often than three-month; neither is automatically cheaper.
- The processing fee, in dirhams.
- The early settlement fee. Capped by the Central Bank at 1% of the balance or AED 10,000 plus VAT, and some banks allow a portion of the balance to be repaid each year at no cost. It sets the price of leaving at the end of the fix — the detail is in our guide to the early settlement fee.
- Any minimum or floor rate. Some contracts set a floor below which the variable rate will not fall even if EIBOR does, which removes the benefit of falling rates.
The refinance horizon
The comparison also tells you when to leave. If your fixed period is ending and you are about to revert to a high margin, the same arithmetic applies to switching: a lower margin elsewhere, net of the fees of moving, usually pays back within one to two years. Whether it does for your balance is covered in is switching your UAE mortgage worth it.Loan interest calculators: flat rates are not comparable
Many people searching for a loan interest calculator in the UAE are looking at personal or car loans rather than mortgages, and those are often quoted on a flat rate — interest charged on the original amount for the whole term rather than on the reducing balance. The number looks far lower than it really is:| Quoted flat rate (AED 100,000 over 4 years) | Monthly instalment | Equivalent reducing-balance rate |
| 3.50% flat | AED 2,375 | 6.58% |
| 4.50% flat | AED 2,458 | 8.36% |
The short version
- Each 0.25% on AED 1.5 million is worth about AED 200 a month and AED 60,000 over the term.
- Compare margins before rates. The introductory rate decides three years; the margin decides twenty-two.
- Break-even between a cheap teaser and a low margin is usually around year five, and EIBOR barely moves it.
- Convert the processing fee into a rate for the period you expect to hold the loan.
- Model the reversion rate plus two points before you commit. That is the number the bank tests you against.