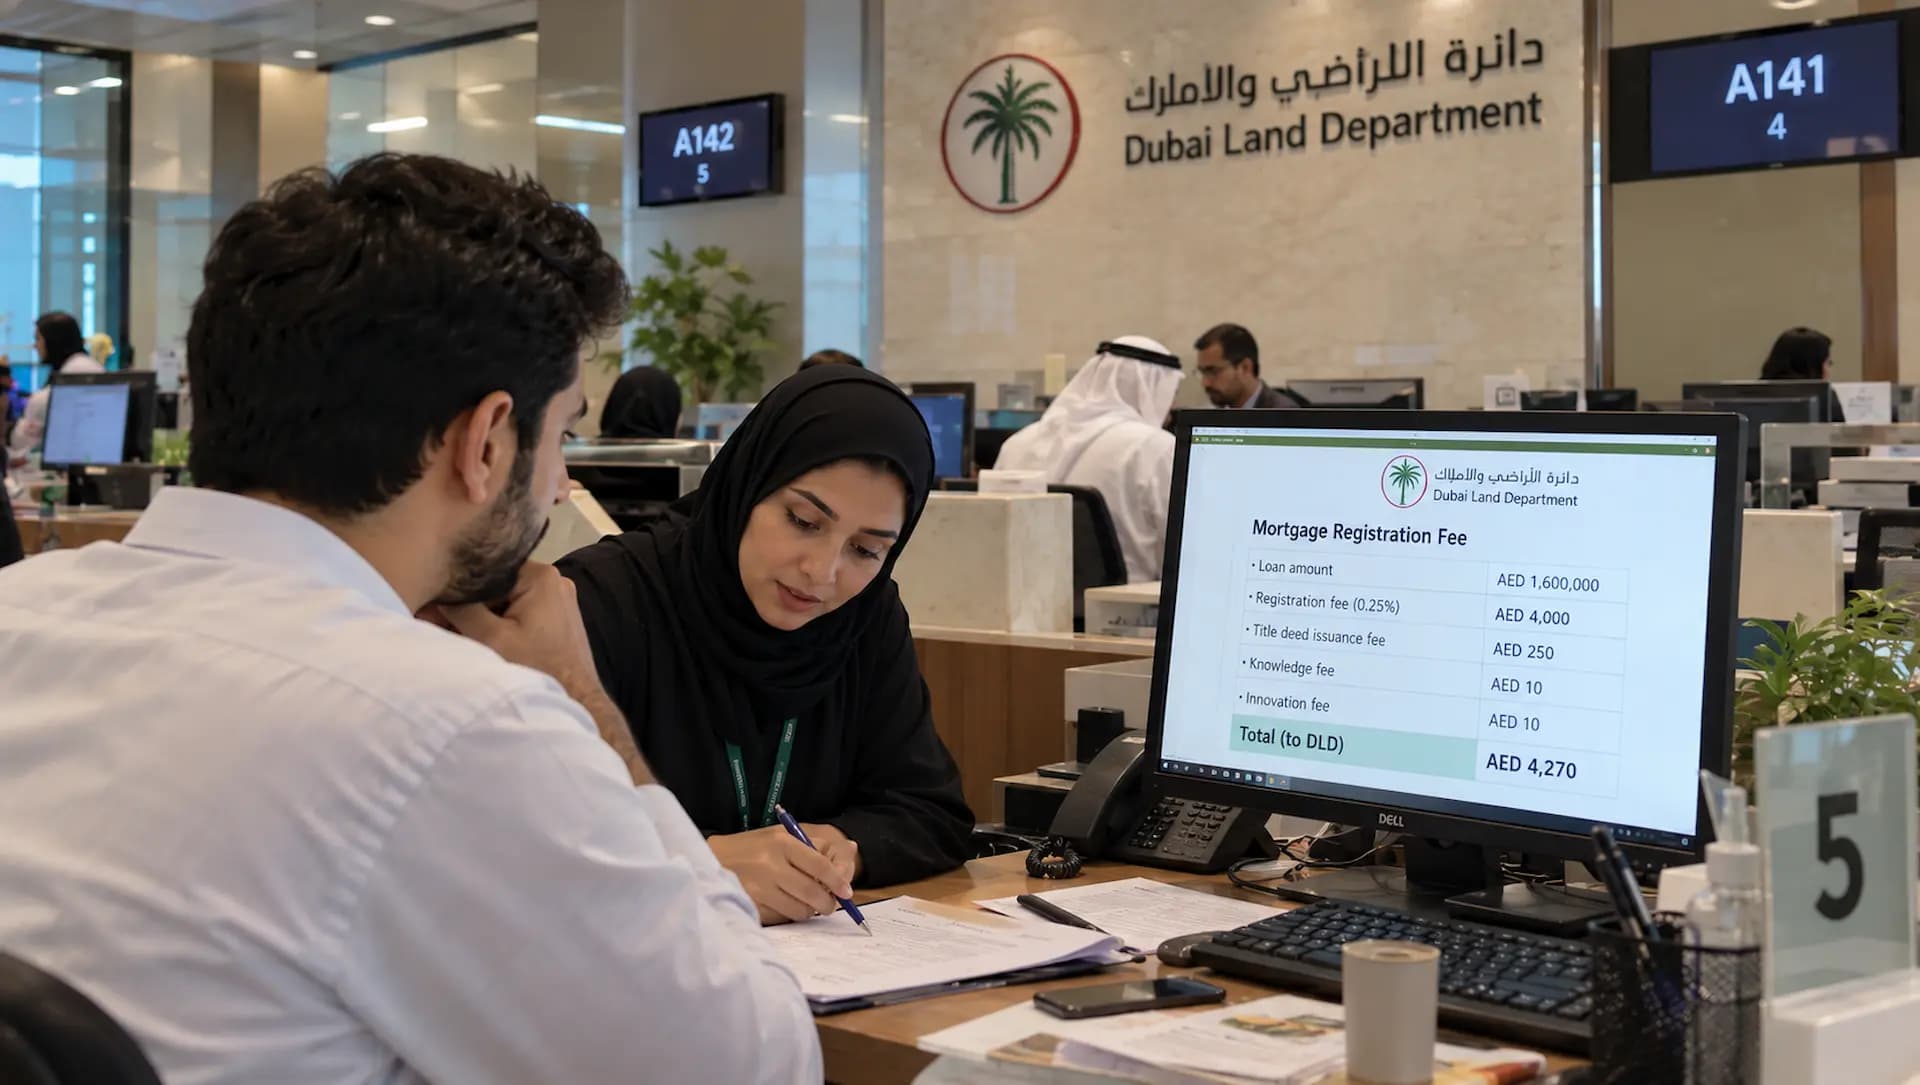
On a AED 1.6 million mortgage, the Dubai Land Department charges AED 4,000 to register the bank’s charge over your property, plus a couple of hundred dirhams in fixed fees. Beside the 4% transfer fee it barely registers.
It matters more than its size suggests. Under Dubai law a mortgage that has not been registered with the Land Department has no legal effect at all — so this small fee is what turns a loan agreement into security a bank can enforce, and what stamps your title deed as encumbered until the day the debt is cleared. It also comes back, in one form or another, every time you increase the loan, move it to another bank, or pay it off.
Three details in that table do most of the work.
The percentage is charged on the loan, not the price. “Mortgage value” means the amount the mortgage secures. On a AED 2 million home bought with a AED 1.6 million loan, the fee is AED 4,000, not AED 5,000. Calculators that apply 0.25% to the purchase price overstate it.
The fixed charges add AED 270 on DLD’s schedule. Many guides quote “0.25% plus AED 290”; DLD’s current service page itemises AED 250 for the deed and AED 20 in knowledge and innovation fees. The difference is trivial, but the published schedule is the one that applies.
The trustee fee usually disappears — if you register on the same day. When a buyer’s new mortgage is registered in the same appointment as the purchase, the service partner fee for the mortgage is waived; DLD’s schedule for the sale of a mortgaged property notes that registering the mortgage the following day costs AED 4,000 plus VAT. In practice this is why the bank’s mortgage registration happens at the trustee office alongside the transfer, and why a delayed bank cheque or a missing mortgage contract at that appointment is expensive.
There is no cap. Unlike the bank’s early settlement fee, which stops at AED 10,000, the Land Department’s percentage runs on the full loan however large it is.
Two of these deserve a closer look.
Switching banks pays the 0.25% again in full. A buyout is registered at DLD as a mortgage transfer, and the percentage is charged on the whole new mortgage, not just on any increase. On a AED 1.5 million balance that is AED 3,750, plus the trustee fee — together more than the outgoing bank’s capped early settlement fee. The full sequence is in the mortgage buyout and balance transfer guide, and whether a switch pays at all in is switching your UAE mortgage worth it.
Paying the loan off does not clear your title deed. Article 20 terminates the mortgage in law the moment the debt is repaid, but the register still shows the property as mortgaged until a release is registered. That needs a release letter from the bank — the clearance letter is capped by the Central Bank at AED 95, and banks must issue liability confirmations within seven business days under the Consumer Protection Standards — and a release application at DLD. It takes ten to fifteen minutes and can be done through the bank’s online mortgage system. People who pay off a mortgage and never register the release discover the problem years later, when they try to sell, gift or remortgage and the title deed still carries the bank’s name.
Every line on that list is now paid in cash, on top of the AED 400,000 deposit. The rest of the schedule is broken down in DLD fees in Dubai and, with the bank’s costs included, in the cost of buying property in Dubai.
What the fee is, exactly
The fee is set out on the Land Department’s own mortgage registration service page:| Line on the DLD schedule | Amount |
| Mortgage registration, ordinary title deed | 0.25% of the mortgage value |
| Title deed issuance | AED 250 |
| Knowledge fee | AED 10 |
| Innovation fee | AED 10 |
| Service partner (trustee) fee, ready property | AED 4,000 + VAT |
| Service partner (trustee) fee, off-plan property | AED 5,000 + VAT |
| Loan amount | 0.25% fee | With DLD fixed fees |
| AED 600,000 | AED 1,500 | AED 1,770 |
| AED 1,200,000 | AED 3,000 | AED 3,270 |
| AED 1,600,000 | AED 4,000 | AED 4,270 |
| AED 2,400,000 | AED 6,000 | AED 6,270 |
| AED 4,000,000 | AED 10,000 | AED 10,270 |
| AED 7,000,000 | AED 17,500 | AED 17,770 |
Why an unregistered mortgage is worth nothing
The law that governs all of this is Dubai Law No. 14 of 2008 Concerning Mortgages in the Emirate of Dubai. Its central provision is short: “A Mortgage will come into effect only when it is registered with the DLD, and any agreement to the contrary will be null and void.” — Article 7(1) That sentence explains the whole fee. A loan agreement between you and your bank is a contract to lend money. It is the registration that converts it into a charge over the property, and the bank will not release funds to the seller until that registration is in place. Several other provisions of the same law shape what the registered mortgage then does:- Only licensed lenders can hold one. Article 4 requires the mortgagee to be “a bank, or a financing company or institution, that is duly licensed and registered with the UAE Central Bank to provide Real Property financing”. A private individual lending you money cannot register a mortgage, which is why informal “security” arrangements between private parties over Dubai property are so fragile.
- First registered ranks first. Under Article 17, “the rank of a Mortgage will be determined by the serial number of registration with the DLD”. If a property ever carried two charges, the earlier registration is paid first from any sale proceeds.
- You cannot sell without the bank’s consent. Article 10 allows the owner to dispose of mortgaged property only with the mortgagee’s approval. This is the legal reason a mortgaged sale in Dubai always runs through a liability letter and a settlement cheque from the buyer’s side.
- It ends when the debt ends — legally. Article 20: “A Mortgage will be terminated upon full repayment of the secured debt.” The annotation on the register, however, stays until a release is registered. More on that below.
- Enforcement runs through the courts. On default, Articles 25 to 28 require the lender to give at least 30 days’ notice through the Notary Public, after which the execution judge can order attachment and sale by public auction. The judge may postpone the auction once, for up to 60 days, and the sale must then take place within 30 days of that period expiring. A registered mortgage gives the bank this route; an unregistered one does not.
Who pays it
The law answers this directly. Article 7(2): “A Mortgagor will be liable for the Mortgage contract registration fees unless otherwise agreed by the parties.” So the default is that you pay, and that is what every bank’s offer assumes. But the words “unless otherwise agreed” are there for a reason. Lenders do sometimes absorb the mortgage registration fee in promotional pricing, particularly for higher-value loans or clients moving salary to the bank. On a AED 4 million loan that is AED 10,270 — worth asking about in the same conversation as the rate and the processing fee, rather than after the offer letter has been signed. The fee also has to be paid in cash. Since 1 February 2025, banks no longer roll purchase fees into the mortgage, and the 0.25% registration charge is part of that cash stack along with the 4% transfer fee and the agency commission. How that changed the amount buyers need on day one is covered in the DLD fee financing ban.Off-plan: registering a mortgage before the property exists
You can mortgage a property that is still under construction, and the same 0.25% applies. Article 24 of the law allows a purchaser of off-plan property to mortgage it “provided that such Real Property Unit or Real Property is registered on the Interim Real Property Register” — the register behind Oqood. Three practical differences from a ready purchase:- The charge sits on the Oqood record, registered through DLD’s service for a sale associated with an initial mortgage, again at 0.25% of the mortgage value.
- The service partner fee is higher where a trustee is used — AED 5,000 plus VAT against AED 4,000 for a ready property.
- At handover the charge converts from the interim register to the title deed, preserving the bank’s security position rather than being registered afresh. Confirm with your lender before drawdown that the Oqood record is verified and that the handover conversion is arranged with their mortgage operations team, because that is where off-plan completions stall.
Islamic home finance: the same fee on a different base
Where the bank finances through Ijara rather than a conventional mortgage, the Land Department registers a lease rather than a mortgage, and the fee is expressed differently. DLD’s finance lease registration service charges 0.25% of the finance rental value, and its Lease To Own registration charges 0.25% of the rental value alongside the usual transfer fees and the same AED 4,000 plus VAT service partner fee. The rate is identical. The base may not be. If the registered rental value is the total of all rentals over the term — principal plus profit — it is a larger figure than the amount financed, and 0.25% of it is a larger fee. Ask your bank which number will appear on the contract before you compare an Islamic and a conventional offer on cost. The structures themselves are explained in how Islamic mortgages work in the UAE.The fee comes back: every later change to the mortgage
Registration is not a one-off. Every material change to the charge goes back through the Land Department, and most of them cost money again.| What you are doing | DLD charge |
| Registering a new mortgage on purchase | 0.25% of the loan + AED 270 |
| Increasing the mortgage with the same bank (top-up, equity release) | 0.25% on the amended mortgage value |
| Changing only the term of the mortgage | AED 1,000 |
| Moving the mortgage to another bank | 0.25% of the new mortgage + AED 270 + AED 4,000 + VAT trustee |
| Releasing the mortgage once it is repaid | AED 1,000 + AED 250 deed + AED 20 + AED 300 + VAT ≈ AED 1,585 |
Where the fee sits in the bigger bill
On a AED 2 million home bought by a resident expat with 20% down, the mortgage registration is one of the smaller lines in roughly AED 145,000 of transaction costs:| Purchase cost on AED 2m with a AED 1.6m loan | Amount |
| DLD transfer fee, 4% of the price | AED 80,000 |
| Agency commission, 2% + VAT | AED 42,000 |
| Bank processing fee | AED 10,500 |
| Mortgage registration, 0.25% of the loan + fixed fees | AED 4,270 |
| Registration trustee | AED 4,200 |
| Valuation | AED 3,150 |
| Title deed, map, knowledge and innovation fees on the sale | AED 520 |
| Total | AED 144,640 |
Before you reach the trustee office
- Calculate the fee on the loan amount, not the purchase price.
- Make sure the bank’s mortgage contracts and cheques will be at the transfer appointment, so the mortgage registers the same day and the separate trustee fee is avoided.
- Ask, before signing the offer, whether the bank will absorb the registration fee. Article 7(2) allows it.
- For off-plan, confirm the Oqood record is verified before any drawdown, and ask how the handover conversion will be handled.
- For Islamic finance, ask which figure — amount financed or total rental — will be registered.
- When the loan is repaid, register the release. Do not assume the bank will do it unprompted.