Before February 2025, a resident expat buying a AED 2 million home in Dubai could walk into the transfer with roughly AED 447,000. Today the same purchase needs about AED 545,000. Nothing about the property, the price or the deposit rule changed. What changed is that the bank stopped lending the fees.
Since 1 February 2025, UAE banks have no longer financed the Dubai Land Department transfer fee, the agent’s commission or the other purchase costs as part of a mortgage. The loan now covers the property — up to the Central Bank’s loan-to-value limit — and nothing else. Every dirham of fees comes from your own pocket, on completion day, on top of the deposit.
The deposit rule is unchanged. The cash requirement went up by AED 97,600 — almost five percentage points of the price — because the fees moved from the loan to your account.
Across price points and buyer types, the cash needed today:
The working rule is simple: take the deposit percentage and add seven to eight points. A 20% buyer needs 27 to 28%. A 40% investment buyer needs around 47%. Fees fall slightly as a share of the price on bigger purchases because some of them are fixed or capped, but never by much. The LTV tiers themselves are in UAE mortgage LTV rules for expats and nationals.
Borrowing AED 120,000 to pay fees can remove more than AED 370,000 from the mortgage you qualify for — and the personal loan carries a higher rate than the mortgage would have. You can test your own figures on the mortgage eligibility calculator.
What actually changed
Before the change, banks routinely added most of the purchase costs to the mortgage. Reporting at the time by The National put it at roughly 80% of the costs, worth around 5% of the property’s value — enough to push a nominal 80% mortgage to an effective loan-to-value near 85%. The same reporting estimated that around 70% of mortgage buyers used the option, which tells you how many household budgets were built on it. The Central Bank instructed banks to stop. Mortgages approved before 1 February were reportedly allowed to keep financed fees provided the transfer completed by 31 March 2025; after that, no exceptions. The fees now paid in cash include:- The DLD transfer fee — 4% of the price
- Agency commission — typically 2% plus VAT
- Mortgage registration — 0.25% of the loan plus fixed charges
- The registration trustee fee — AED 4,200 including VAT for most homes
- Title deed and DLD administration charges
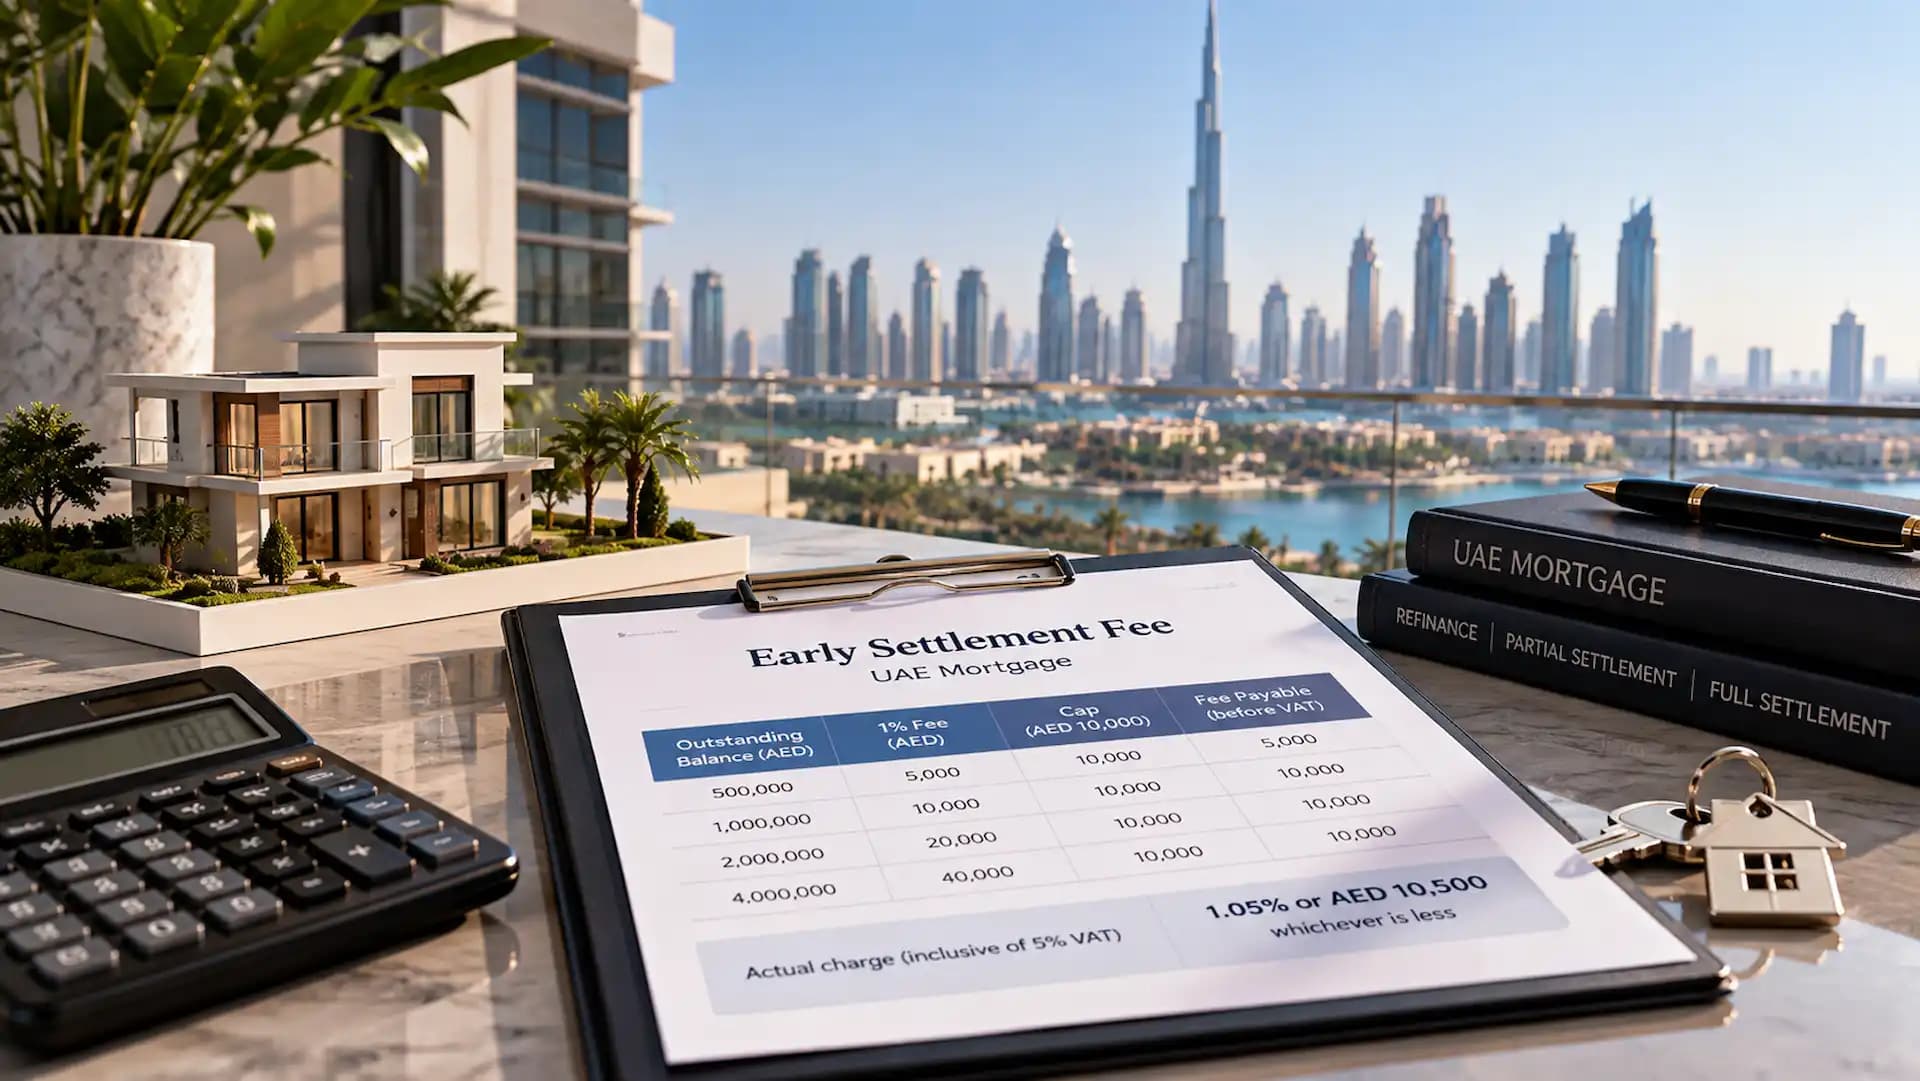
- The bank’s own costs — processing fee and valuation
Why you will not find “the circular”
People searching for the regulation behind the ban usually come up empty, and there is a reason. The Central Bank’s Regulations Regarding Mortgage Loans do not mention fees at all. What they contain are two rules the old practice was quietly working around. Article 3 sets the loan-to-value limits against the value of the property. For a resident expat’s first home that is “maximum 80% of the value of the property” up to AED 5 million and 70% above it; for nationals, 85% and 75%; for any second or investment property, 60% for expats and 65% for nationals; and 50% for off-plan. A loan that includes the fees on top of 80% of the property’s value is, measured against the property, more than 80%. Article 2(4) requires the down payment to come from the borrower. “The level of down payment required from the borrower should be drawn from the borrower’s own resources and not from other sources of borrowing.” The point of a deposit is that the buyer has their own money at stake. Financing the fees diluted that, because cash that would have gone on fees could go into the deposit instead. The February 2025 instruction reached banks as supervisory direction rather than as an amendment to the published rulebook. Its effect is to make the loan-to-value cap mean what it says: the mortgage may fund the property up to the limit, and no further. This is also why “can I put down more and have the bank finance the fees instead?” has no useful answer. You can always borrow up to the LTV limit on the price. What you cannot do is borrow beyond it to cover costs. If you have more cash than the minimum deposit plus fees, you simply borrow less.What it does to the cash you need
Take the AED 2 million home, a resident expat, first property, 20% down:| Before February 2025 | Since February 2025 | |
| Mortgage | AED 1,697,600 | AED 1,600,000 |
| Effective loan-to-value | 84.9% | 80.0% |
| Deposit | AED 400,000 | AED 400,000 |
| Fees paid in cash | AED 47,040 | AED 144,640 |
| Total cash on completion | AED 447,040 | AED 544,640 |
| Cash as a share of the price | 22.4% | 27.2% |
| Purchase | Buyer | LTV | Deposit | Fees | Total cash | % of price |
| AED 1,000,000 | Expat, first home | 80% | AED 200,000 | AED 79,540 | AED 279,540 | 28.0% |
| AED 1,500,000 | Expat, first home | 80% | AED 300,000 | AED 113,140 | AED 413,140 | 27.5% |
| AED 2,000,000 | Expat, first home | 80% | AED 400,000 | AED 144,640 | AED 544,640 | 27.2% |
| AED 3,000,000 | Expat, first home | 80% | AED 600,000 | AED 207,640 | AED 807,640 | 26.9% |
| AED 6,000,000 | Expat, first home | 70% | AED 1,800,000 | AED 395,140 | AED 2,195,140 | 36.6% |
| AED 2,000,000 | National, first home | 85% | AED 300,000 | AED 144,890 | AED 444,890 | 22.2% |
| AED 2,000,000 | Expat, investment | 60% | AED 800,000 | AED 143,640 | AED 943,640 | 47.2% |
The part nobody mentions: it saves you money
Financing the fees felt painless because the cost was spread over 25 years. It was not free. On the example above, the AED 97,600 that used to be borrowed would have cost:- AED 515 a month on the instalment — AED 8,951 against AED 8,437 at 3.99%
- AED 56,789 in interest over the full term, more again once the rate reverts
- Higher life cover, which is priced on the outstanding balance
Who it hits hardest
First-time buyers with savings that just covered the deposit. This was the group the old practice served. If your savings reach 20% and not much more, your realistic price ceiling has dropped by roughly a fifth. A buyer with AED 450,000 who could have bought at AED 2 million in 2024 is now looking at around AED 1.65 million. Buyers above AED 5 million. The fees are proportional, but the LTV drops to 70%, so the cash requirement jumps to around 37% of the price. Investors and second-home buyers. At 60% LTV the deposit already dominated, but nearly half the price in cash is a material hurdle for anyone recycling equity. Non-residents, whose lenders typically cap loans well below resident levels, now carry the same full fee load on top. Their constraints are covered in Dubai mortgages for non-residents. Least affected: off-plan buyers. The 4% DLD fee on an off-plan purchase is paid at Oqood registration, at booking, before any mortgage exists — so it was always cash. Off-plan buyers financing at handover were less reliant on fee financing in the first place, which is one reason developer payment plans gained ground after the change.Workarounds that hold up
A developer DLD fee waiver. Many developers absorb the 4% transfer fee as a sales incentive — one listings platform counted 21 live developer offers in July 2026, with waivers among the most common. On the median H1 2026 off-plan apartment of AED 1,346,000, that is worth AED 53,840 in real cash. Two caveats: waivers are mostly on off-plan stock, and they tend to arrive bundled with incentives that are harder to price, so compare the price per square foot against similar units without the offer before treating the waiver as a saving. Negotiating with the seller. On a ready resale, the fee itself cannot move, but the price can. In a market where buyers need 27% in cash, sellers face a smaller pool of qualified buyers, and that is leverage. Buying within your cash, not your borrowing. Work out the price from the cash you have, not from the loan you can get. Divide your available cash by 0.275 for a first home under AED 5 million. That is your ceiling, regardless of what an eligibility calculator says. Keeping the bank’s costs down. Processing fees and valuation are the only items in the stack that are commercial rather than statutory. Some lenders waive or discount processing fees, and the mortgage registration fee can be absorbed by the bank by agreement. Together they can be worth AED 10,000 to AED 15,000.The workaround that backfires: a personal loan
The obvious idea is to take a personal loan for the fees. It usually makes the purchase harder, not easier. First, if any of that money goes towards the deposit, it breaches Article 2(4) — the deposit must come from your own resources, and lenders check the source of funds. Fees are not covered by that wording, but the bank will still see the loan on your Al Etihad Credit Bureau report and ask why it appeared weeks before a property purchase. Second, and more decisively, it damages your affordability. A AED 120,000 personal loan over four years at 6.5% costs AED 2,846 a month, and that counts in full against your 50% debt burden ratio. Because the mortgage is tested at a stressed rate, the effect on what you can borrow is far larger than the loan itself:| Income AED 30,000, existing commitments AED 3,500 | Maximum mortgage |
| Without a personal loan | AED 1,504,282 |
| With a AED 120,000 personal loan | AED 1,132,032 |
| Borrowing power lost | AED 372,250 |
How to plan around it
- Budget cash at deposit plus 7.5% for a ready purchase, and get every line in writing before you make an offer. The full list, with worked examples, is in the cost of buying property in Dubai.
- Keep the cash liquid and visible in an account in your name for at least the months before application. Banks look at where it came from.
- Run the numbers on the reversion rate, not the introductory rate, so a lower loan does not tempt you into a longer tenure you do not need.
- Sequence the cheques for transfer day: the deposit balance and the fees go to different parties, and a missing manager’s cheque delays the mortgage registration — which, if it slips to the next day, costs another AED 4,000 plus VAT.