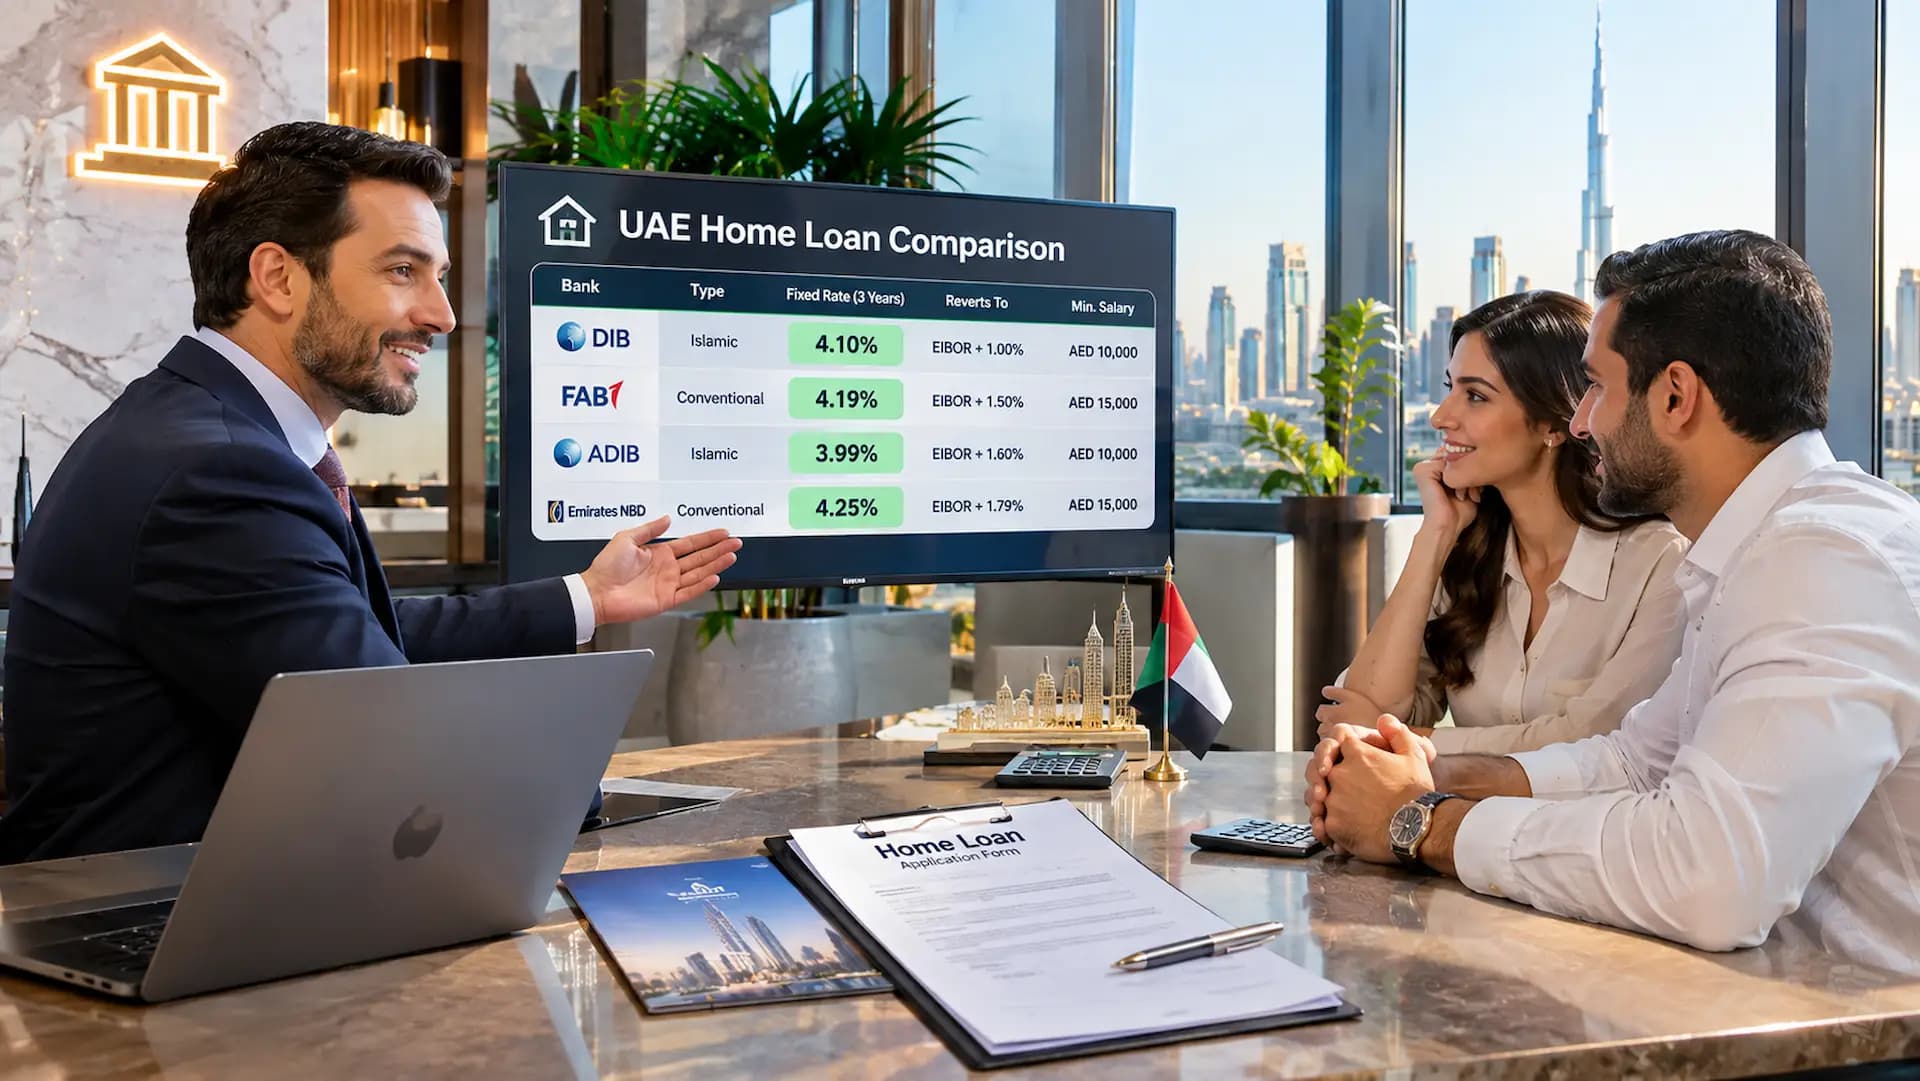
Refinancing is a timing decision. The same switch that saves one homeowner AED 70,000 can cost another AED 7,000, and the difference rarely comes down to the rate alone. It comes down to how much you owe, how long you will keep the new deal, what your own bank will offer, and whether anything has changed since you last borrowed.
This guide is about recognising the right moment, and the wrong one. If you already know you want to switch and need the full cost breakdown, see UAE mortgage refinance: is switching worth it? To test your own numbers, use our refinance calculator.
Based on 20 years remaining. With 10 years left, the required cuts are slightly higher, for example 0.76 points rather than 0.71 points for AED 1 million over three years. A processing fee raises them further.
Two things follow. On a large loan you will keep for three years or more, even half a point is usually worth having. On a AED 500,000 loan you might sell within two years, you need a cut of nearly 1.5 points, which is more than most borrowers will ever see unless they are coming off a reversion rate.
The early settlement fee is a large part of those costs; how it is capped is explained in the early settlement fee.
Over three years, Offer B costs about AED 53,900 less, despite the higher headline rate, because Offer A reverts to a high margin after just twelve months. Always check how long the rate lasts and what it becomes.
If you miss the date, do not rush. A month or two on the reversion rate costs less than locking into the wrong deal for three years.
The short answer
It is usually a good time to refinance when:- Your fixed period ends within the next three months
- The rate cut is large enough for your balance (see the table below)
- You will keep the new deal for at least two to three years
- You want to change the loan itself: fix the rate, switch to Islamic finance or release cash
- Your balance is small or you will sell within about a year
- Your own bank will reprice you close to the market rate
- Your property has fallen in value, or your income or job has changed
- The new offer is a short teaser rate with a high margin afterwards
Good times to refinance
1. Your fixed period is about to end
This is the most common trigger, and for good reason. UAE mortgages are usually fixed for one to five years, then revert to three-month EIBOR plus a margin. With EIBOR at about 4.32% in early November 2026, a typical reversion margin of 1.75% to 1.99% means a rate of roughly 6.1% to 6.3%, well above the 3.75% to 4.4% that banks are offering new customers on fixed deals. How the benchmark moves is tracked in 3-month EIBOR in the UAE. On a AED 1.4 million balance with 20 years left, moving from 3.99% to 6.31% would raise the payment from about AED 8,476 to AED 10,282 a month. The three months before your fixed rate ends are the natural window to act.2. The rate gap is big enough for your balance
Switching costs are largely fixed. The settlement fee is capped at AED 10,500, and the trustee and valuation fees do not grow with your loan. So the bigger your balance, the smaller the rate cut you need to recover them. The table below shows what that means.3. You want certainty for the next few years
If you are on a variable rate and plan to stay in the home, fixing for three to five years protects your budget. It is a reasonable move whenever you would struggle with a higher payment, provided the fixed rate is not far above your current one. The trade-offs are set out in fixed vs variable mortgages in the UAE.4. Your circumstances have improved
A higher salary, a move to an employer whose salary you can transfer to a lender, a stronger credit record or a lower loan-to-value can all qualify you for better pricing than when you first borrowed. Banks rarely reprice you automatically for these. A new application can.5. You want to change the loan, not just the rate
Refinancing is also the way to shorten your term, move to or from Islamic finance, or borrow against your equity. Each changes the calculation. How Islamic and conventional pricing compare is set out in Islamic vs conventional mortgages, and raising cash is covered in equity release in Dubai.The minimum rate cut that makes switching worth it
This table shows roughly how far a new fixed rate needs to be below the rate you would otherwise pay before switching banks breaks even. It assumes you are currently facing 6.31%, take a new rate fixed for the whole period you keep it, and pay the standard Dubai switching costs with no processing fee.| Balance | Switching costs | Keep it 1 year | Keep it 2 years | Keep it 3 years | Keep it 5 years |
| AED 500,000 | about AED 14,200 | 2.86 points | 1.44 points | 0.97 points | 0.59 points |
| AED 1,000,000 | about AED 20,700 | 2.09 points | 1.05 points | 0.71 points | 0.43 points |
| AED 1,500,000 | about AED 22,000 | 1.48 points | 0.74 points | 0.50 points | 0.31 points |
| AED 2,500,000 | about AED 24,500 | 0.99 points | 0.50 points | 0.34 points | 0.21 points |
When not to refinance
1. Your balance is small or your remaining term is short
The table shows why. Fixed costs dominate on small loans. Below roughly AED 500,000, a switch only pays if the rate gap is large and you will keep the new deal for several years.2. You expect to sell soon
If you refinance and then sell, you pay an early settlement fee twice: once to leave your current bank and again when the sale clears the new loan, unless the new lender waives it on sale. Even with a large rate gap, the timing is tight. Moving AED 1.4 million from 6.31% to 3.99% leaves you about AED 5,500 worse off after six months, roughly AED 10,600 better off after a year and AED 26,600 better off after 18 months, before any second settlement fee. If the new bank charges the full AED 10,500 again on sale, a sale after one year only breaks even. With a smaller gap, a sale within one to two years usually wipes out the saving.3. Your own bank will reprice you
Staying with the same bank usually avoids the settlement fee, new Land Department registration and the trustee fee. A retention offer half a point above the best market rate can still be the cheaper choice, so ask before applying elsewhere and compare both in the calculator.4. Your property has fallen in value
A new bank lends against its own valuation, within the Central Bank’s loan-to-value limits. ValuStrat reported Dubai apartment values about 5% lower year on year in August 2026. If you owe AED 1.45 million and the flat now values at AED 1.75 million, the maximum an expatriate can borrow on a first home is 80%, or AED 1.4 million, so you would need about AED 50,000 in cash to switch. How valuers reach their figure is explained in property valuation for a UAE mortgage.5. Your income, job or debts have changed
A new lender assesses you from scratch, at its own stress rate. If you are on probation in a new job, have recently become self-employed, rely more on commission than before, or have taken on a car loan, you may be offered less or declined. If you want to stretch the term to reduce your payment, your age also limits it: usually 65 at the end of the loan for salaried borrowers. In those cases, a repricing with your current bank is often the safer route. How lenders reassess affordability is explained in how the debt burden ratio affects your mortgage.6. The new offer is a teaser
A very low rate for one year can look better than it is. Compare two offers on AED 1.4 million over three years:| Offer A | Offer B | |
| Fixed rate | 3.75% for 1 year | 4.10% for 3 years |
| Then | EIBOR + 1.99% | EIBOR + 1.00% |
| Payment in year 1 | AED 8,300 | AED 8,558 |
| Payment in years 2 and 3 | AED 10,193 | AED 8,558 |
7. Your current fixed rate is still competitive
If you locked in a low rate and it has a year or more to run, breaking it to chase a slightly lower one rarely pays. You would pay the settlement fee to give up a deal that is already cheap. Wait until it is close to ending.8. The property carries extra conditions
If your home supports a Golden Visa, is held jointly with someone abroad, or still has developer conditions attached, a switch involves extra no-objection letters and paperwork. It can still be done, but build in more time and make sure every condition can be met before you commit.A 90-day refinancing plan
If your fixed period is ending, this timeline gives you room to compare properly without paying the reversion rate for longer than you need to:| When | What to do |
| 90 days before | Find out your reversion rate and ask your bank for a retention offer in writing |
| 75 days before | Get two or three outside offers, including any fee waivers |
| 60 days before | Run the numbers for each offer, including your bank’s, over the years you expect to keep the deal |
| 45 days before | Apply to your chosen lender and book the valuation |
| 30 days before | Receive the final offer, then request the liability letter from your current bank |
| Before the end date | Settle and register the new mortgage, following the mortgage buyout steps |
Questions to ask yourself first
- What will I pay if I do nothing? That is the rate to beat, not the one you pay today.
- How long will I realistically keep this property and this loan?
- What has my own bank offered?
- Has anything changed in my income, job, debts or the property’s value?
- After all costs, how many months until I am ahead?